
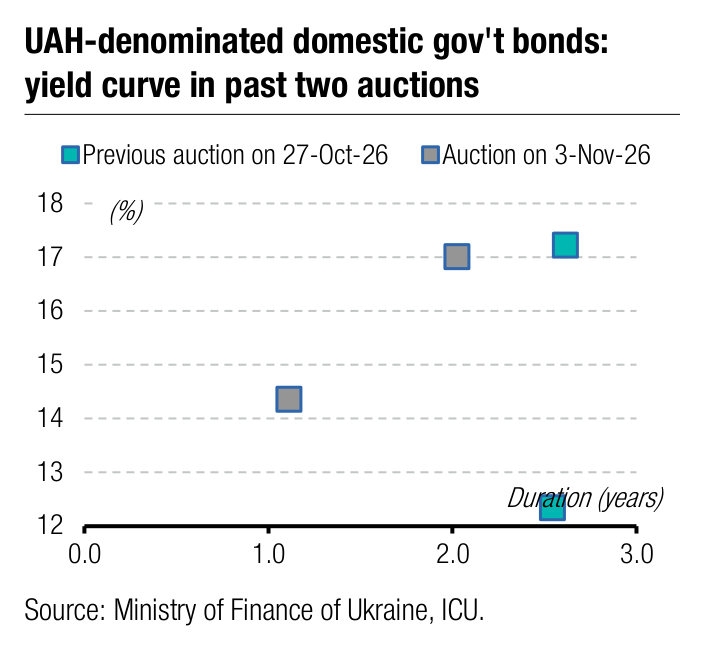
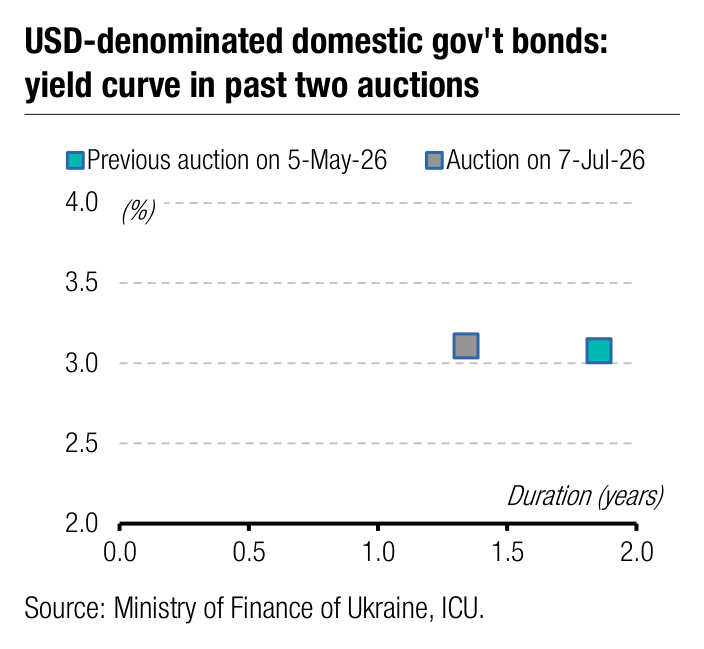
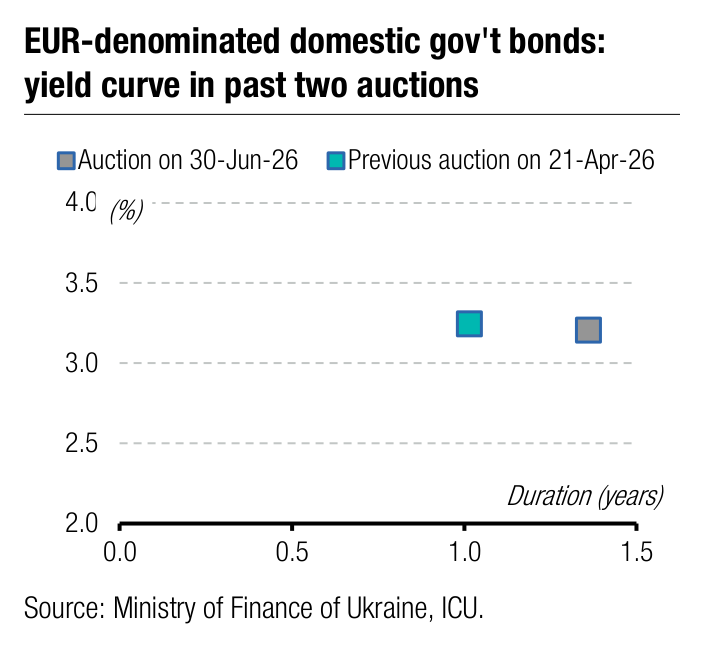
At yesterday's primary auction, the Ministry of Finance did not respond to the National Bank's key policy rate hike. In truth, the auction participants themselves left the ministry no opportunity to do so.
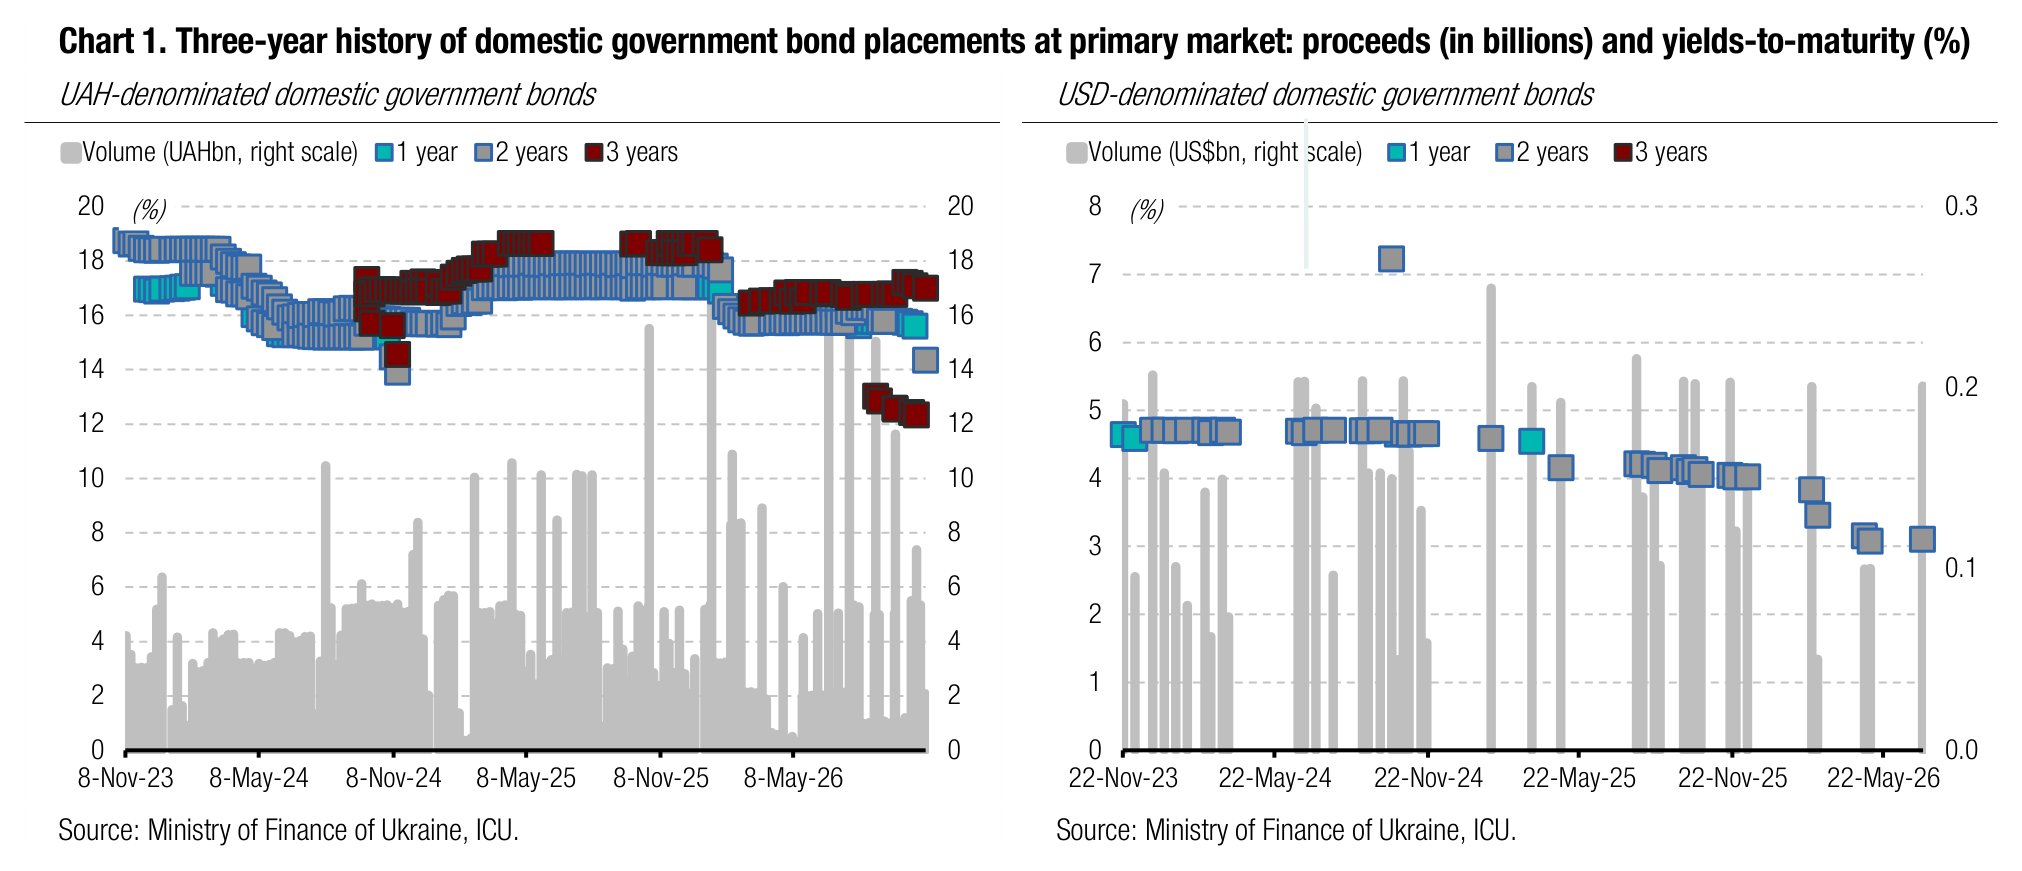
The new "one-year" military bill, maturing in January 2028, attracted 33 bids totalling UAH3.7bn—an oversubscription of nearly 90% relative to the cap. Bids ranged from 14.9% to 16%, but the cap was reached at 15.1%. While this is 15bp higher than the cut-off rate for 11-month bonds, it remains 5bp below the cut-off level for similar bonds issued before the National Bank began tightening monetary policy.
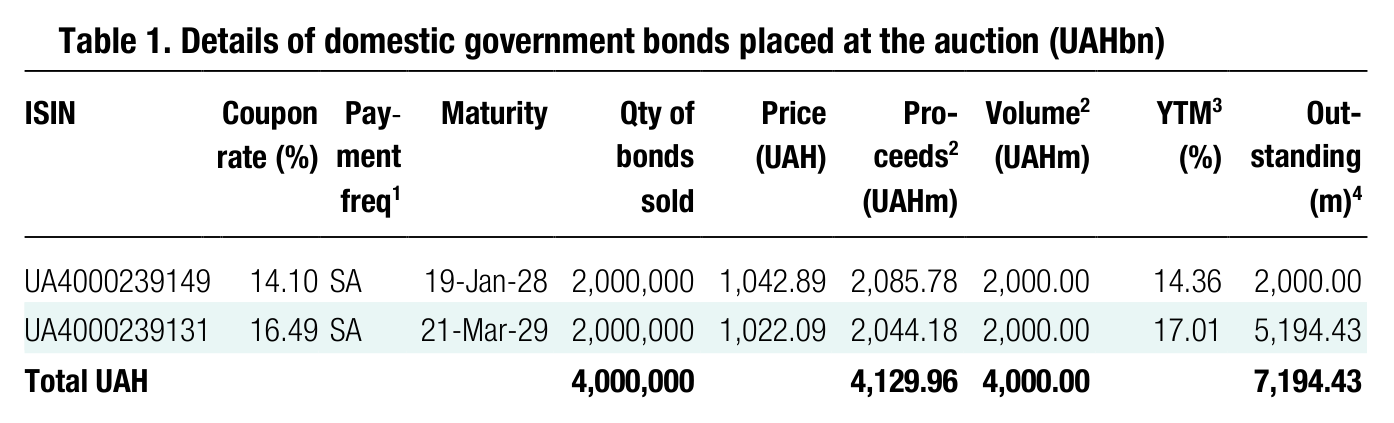
Note: [1] payment frequency abbreviations: M - monthly, Qtly - quarterly, SA - semi-annually, @Mty - at maturity date; [2] proceeds and volumes for the USD-denominated bonds are calculated based on the previous day's exchange rate 44.48/USD, 51.04/EUR; [3] yields on coupon-bearing bonds are effective yields to maturity. Sources: Ministry of Finance of Ukraine, Bloomberg, ICU.
Bonds maturing in the spring of 2029 drew slightly fewer bids—29 in total—but volume was 2.2 times larger than the cap. The bid range here was narrower, spanning 16.3% to 17%; however, the entire supply was absorbed at the minimum rate. Consequently, the Ministry of Finance set both the cut-off rate and the weighted average rate at 16.3%.
Thus, the Ministry of Finance did not need to borrow less than planned to keep yields stable; it simply met the bids submitted at the lowest rates.
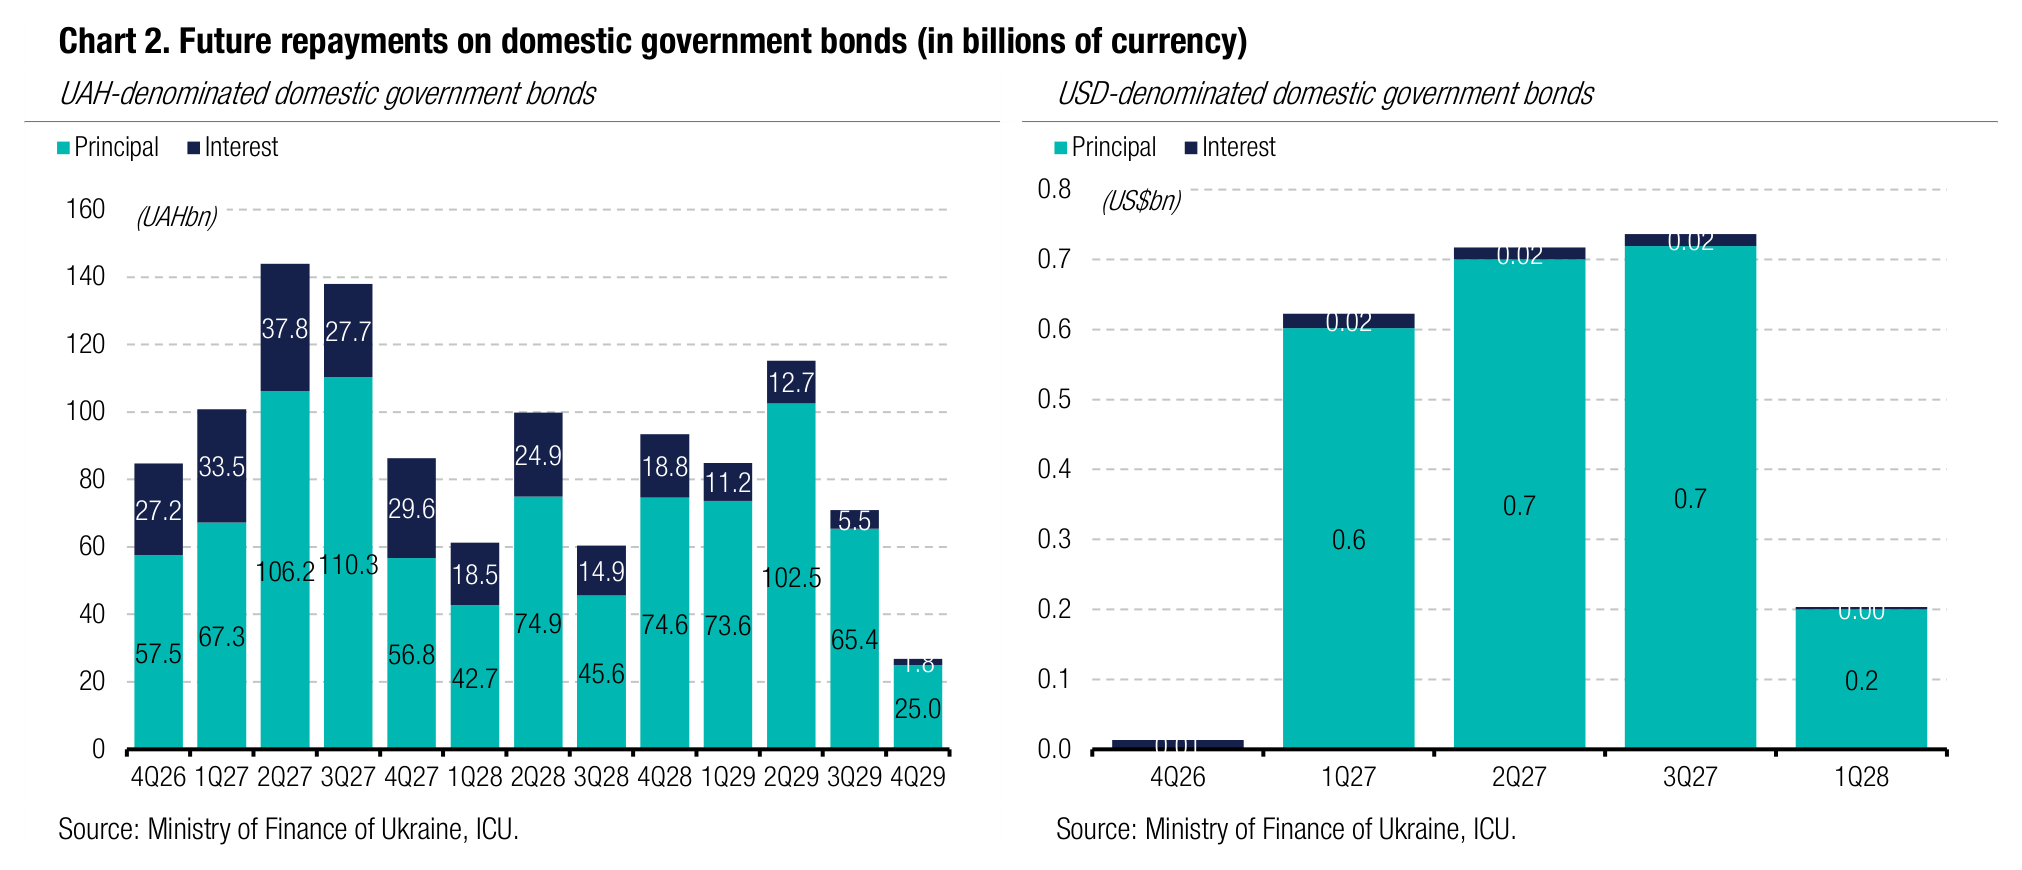
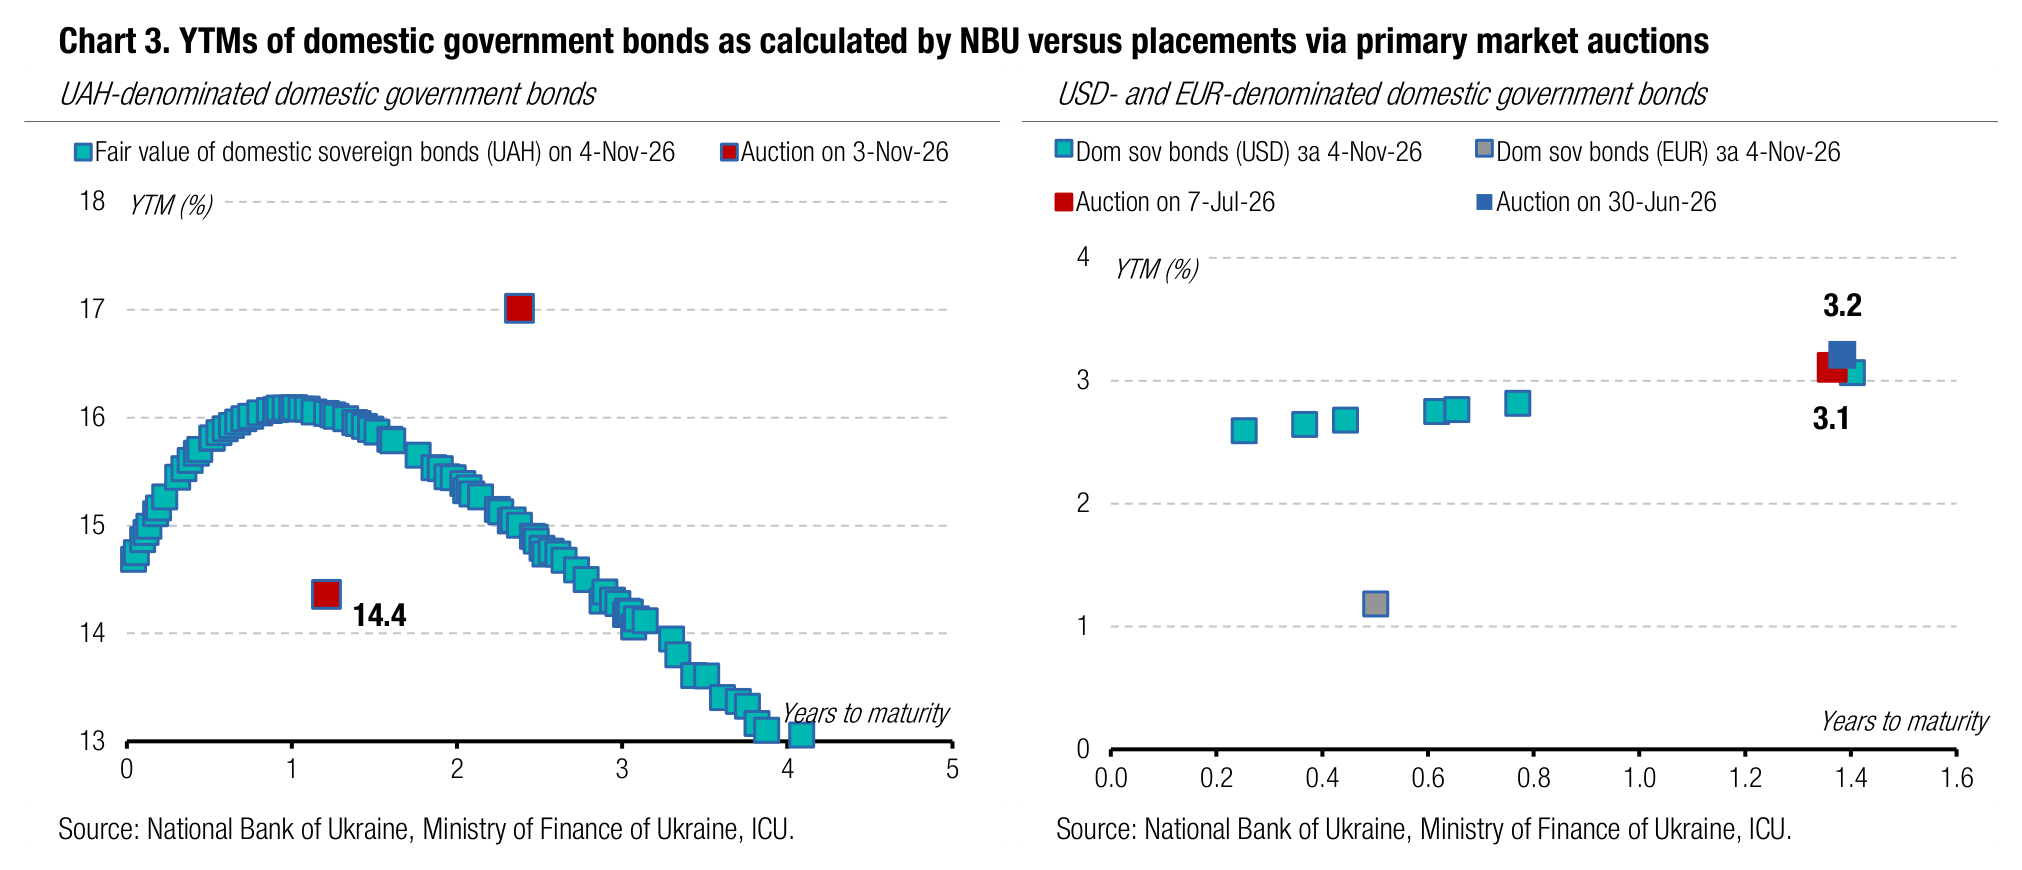
Appendix: Yields-to-maturity, repayments