
Ukrainian bond market
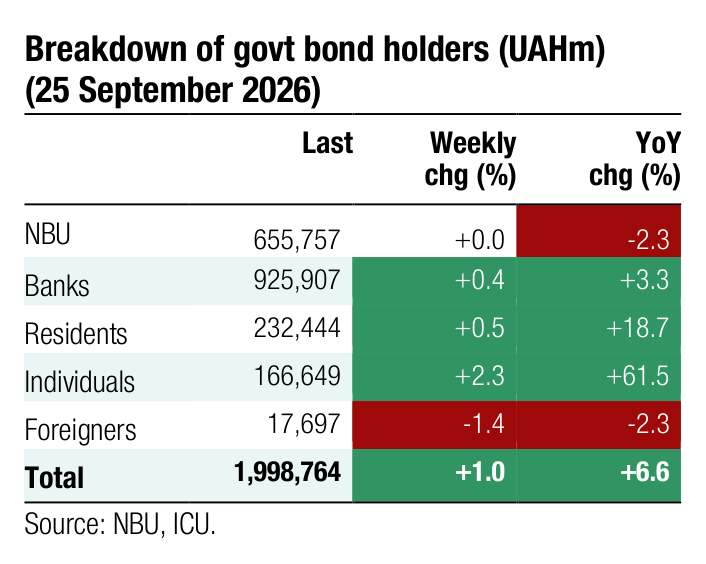
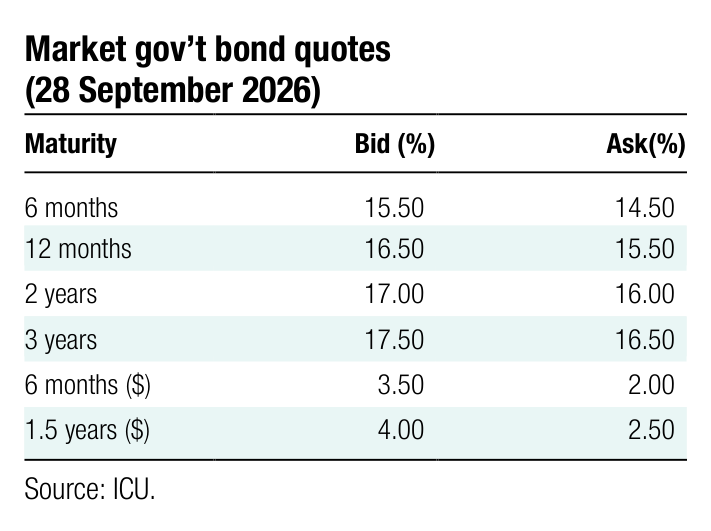
MoF stands firm on rates
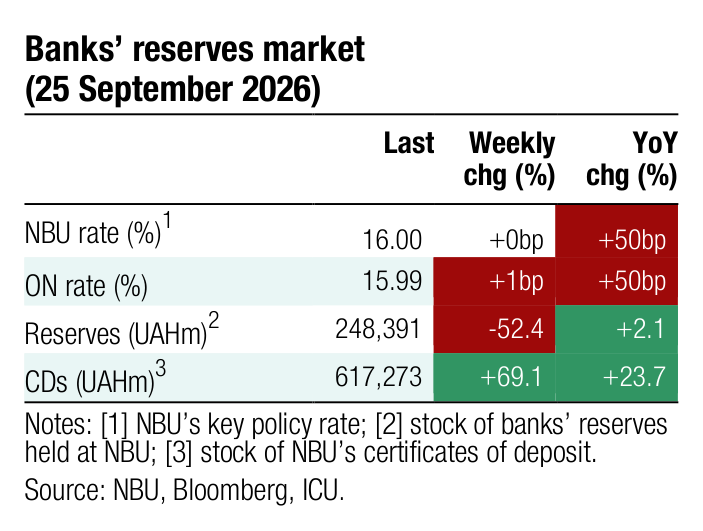
Last week saw the first bond auction following the NBU's key policy rate hike. The ministry, expectedly, reaffirmed its stance on resisting the NBU move and keeping bond yields unchanged.
The one-year bond saw a 2.5x bid-to-cover ratio, so MoF faced no challenges in maintaining yields at the long-established level. However, for 2.5-year paper, the ministry decided to reject the two largest bids to keep the cut-off rate unchanged at 16.10% and sold only UAH283m of bonds. Strong demand for a reserve note pushed the cut-off rate down by another 32bp to 12.18%. See details in the auction review .
Accounting for the reserve-bond exchange auction held on Wednesday, the ministry issued nearly UAH19bn of bonds over the week, slashing the remaining borrowing target for 4Q26 to UAH59bn. That leaves UAH20bn to be raised in October to refinance reserve bonds and then just UAH39bn would be left to be raised through regular and military bonds.
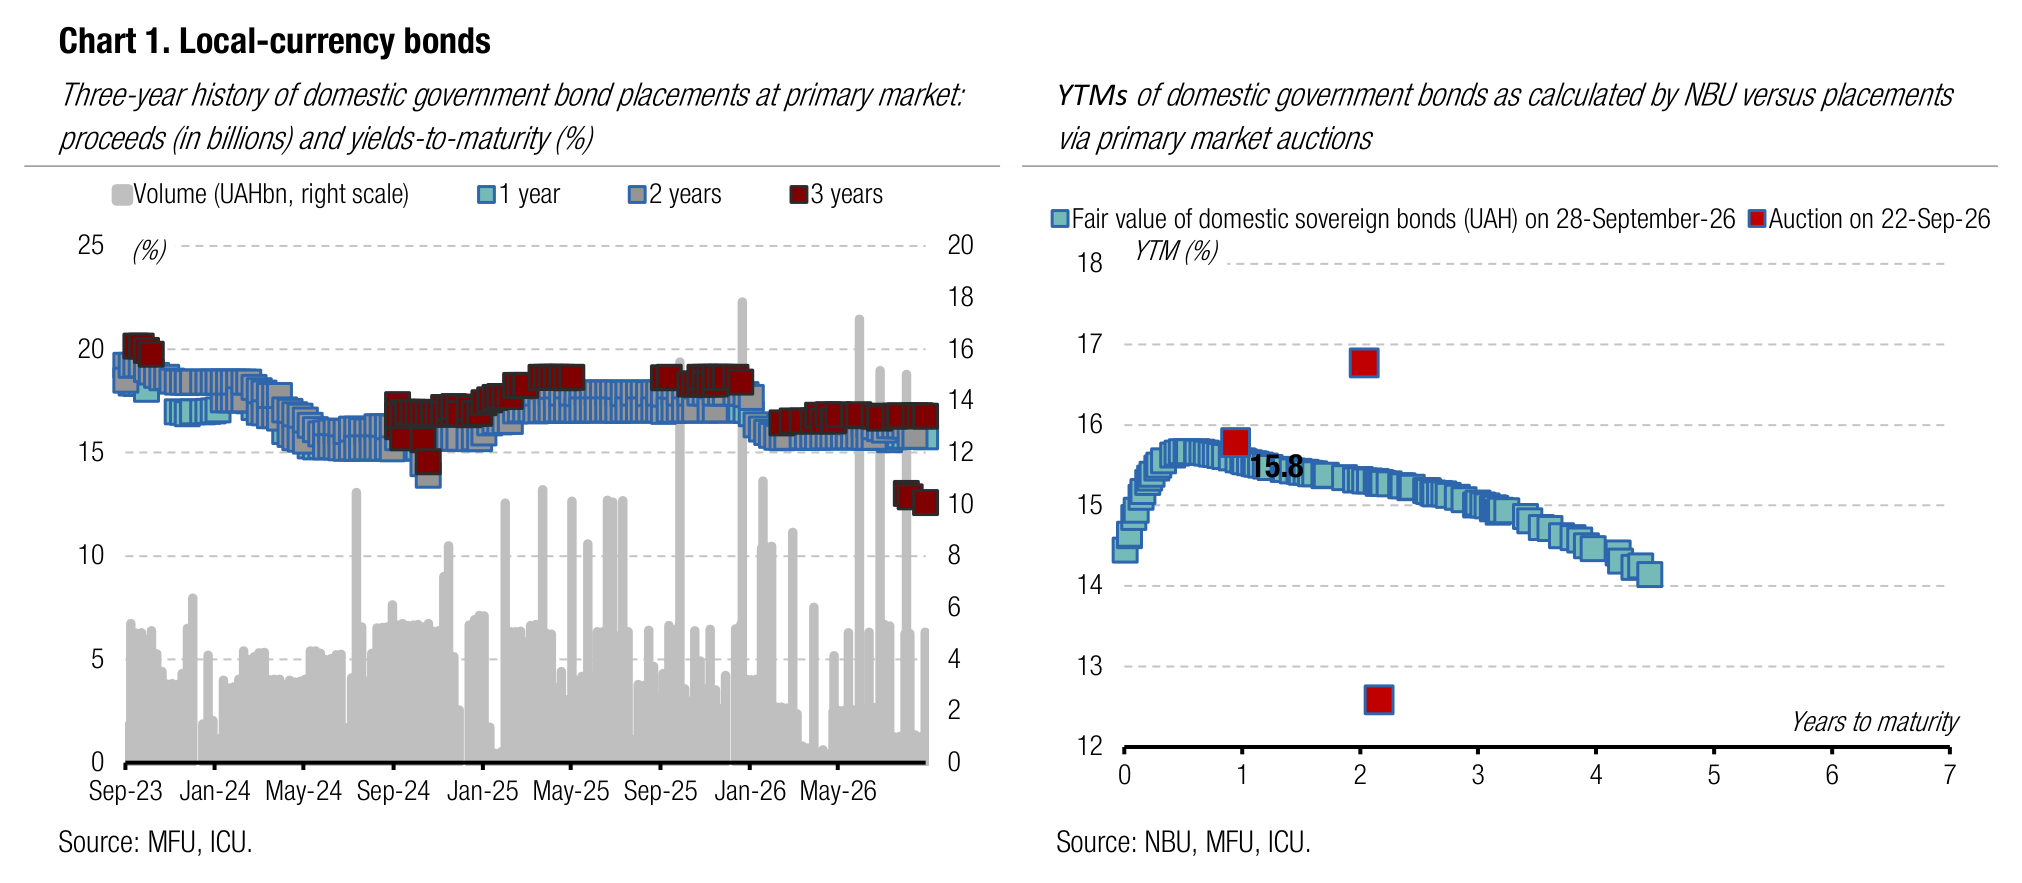
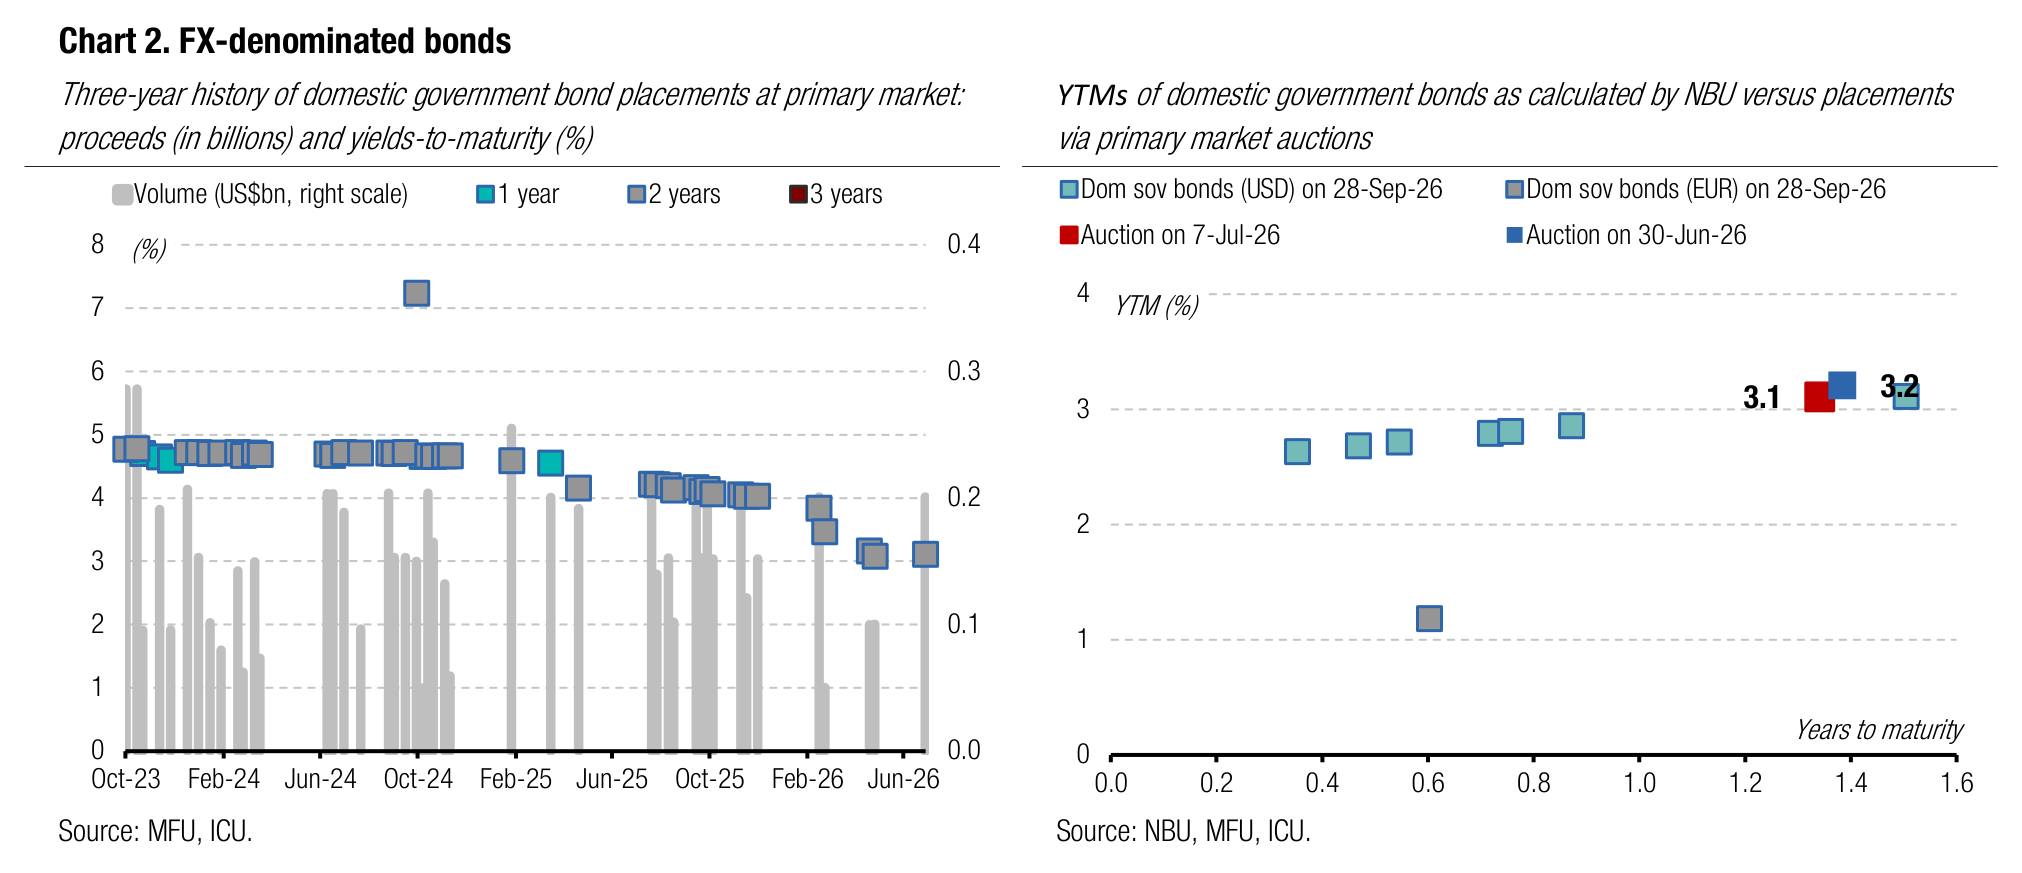
ICU view: As expected, the Ministry of Finance maintained its firm stance and kept primary market bond yields largely unchanged, thus fully ignoring the NBU cumulative key policy rate hike of 100bp since the end of July. According to NBU's current forecast, the key policy rate will remain at its current level of 16% for the next seven months. The MoF continues to raise funds primarily by placing longer-dated bonds whose pricing is shaped not only by the current key policy rate, but also by future rate expectations. We do not anticipate any changes to the MoF's bond-pricing stance in the near term, particularly if the current domestic borrowing plan for 2026 remains unchanged. However, should the domestic borrowing target for 4Q26 be significantly raised, the Ministry of Finance may become more lenient on bond yields towards the end of the year.
Eurobonds under pressure from global sell-off
Ukrainian Eurobonds came under pressure again amid rising yields in global markets, with amplitude again increased due to Ukraine’s outsized vulnerability to global geopolitical jitters.
Last Wednesday marked the start of a global bond sell-off triggered by a significant rise in yields on US Treasuries and debt securities of several developed European countries, which, in turn, drove down prices for EM bonds. Ukrainian Eurobonds reacted accordingly: on Wednesday, prices fell by over 3% on average, with drops reaching 4% for some paper.
On Thursday, holders of Ukrainian securities got some relief from the news coming from the 81st session of the UN General Assembly, where the presidents of the US and Ukraine met. Consequently, Ukrainian Eurobond prices rose on Thursday and Friday.
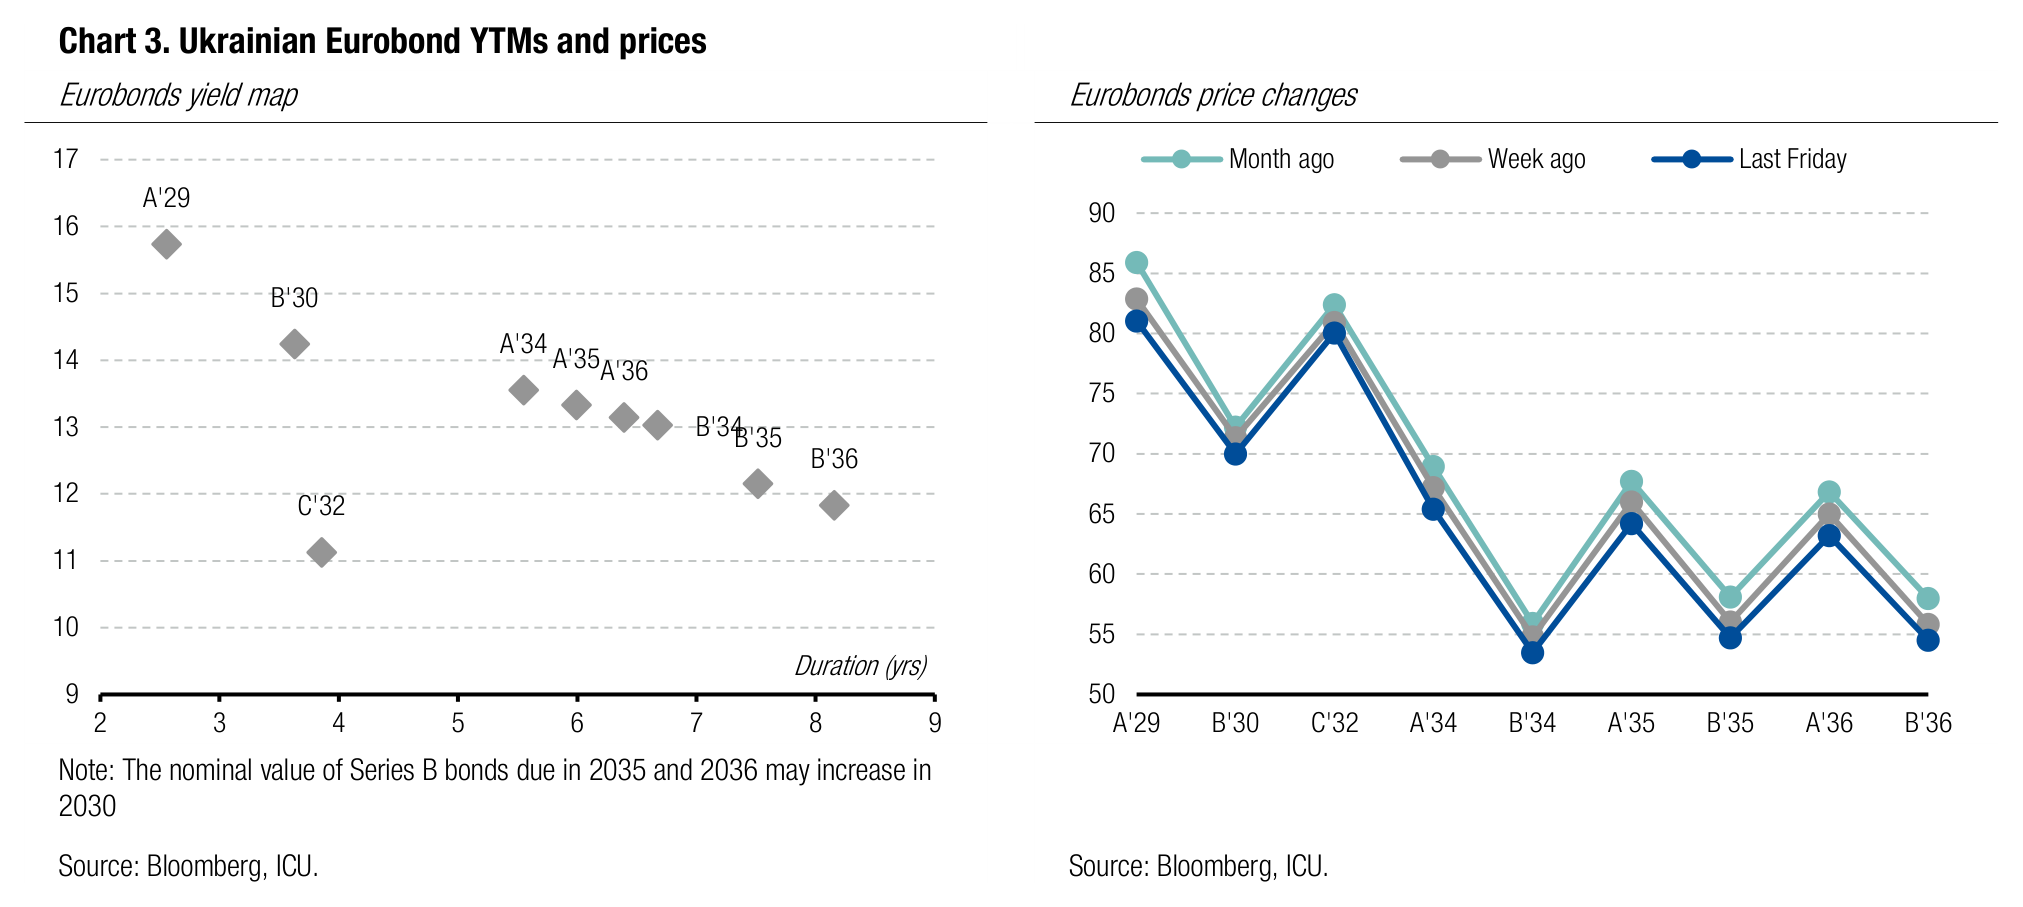
ICU view: Last week, once again, demonstrated that the volatility of Ukrainian Eurobonds significantly exceeds that of other EM bonds, again proving their high-beta status. Investors tend to react with poorly justified optimism to any indicators of progress toward a peace deal. Nevertheless, we remain sceptical about the parties reaching tangible negotiating results in the foreseeable future and expect continued downward pressure on Ukrainian securities in the coming months.
Foreign exchange market
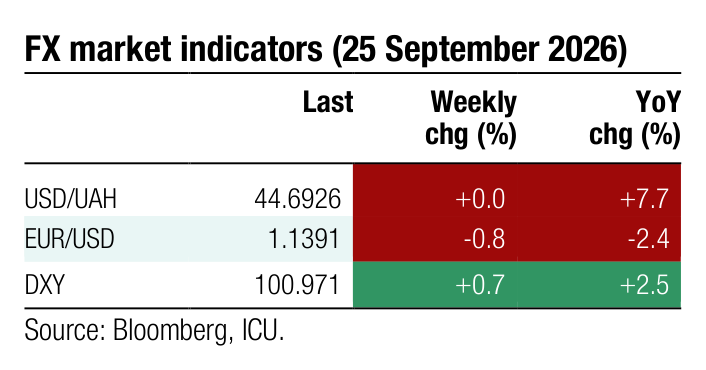
Hryvnia rate volatility up significantly
Last week, the NBU once again demonstrated that the hryvnia exchange rate can move in both directions, though the central bank appears reluctant to devalue the hryvnia further to above the UAH45/US$ mark.
The market's foreign currency shortage remained close to US$0.8bn—consistent with the previous few weeks—so NBU interventions also remained close to US$1.2bn. At the same time, the National Bank allowed the US dollar to appreciate over several days last week, bringing the official exchange rate to almost UAH45/US$ by Thursday. However, on Friday, the NBU reversed the trend, pushing the rate back down to close the week at UAH44.84/US$—an increase of 0.4% WoW.
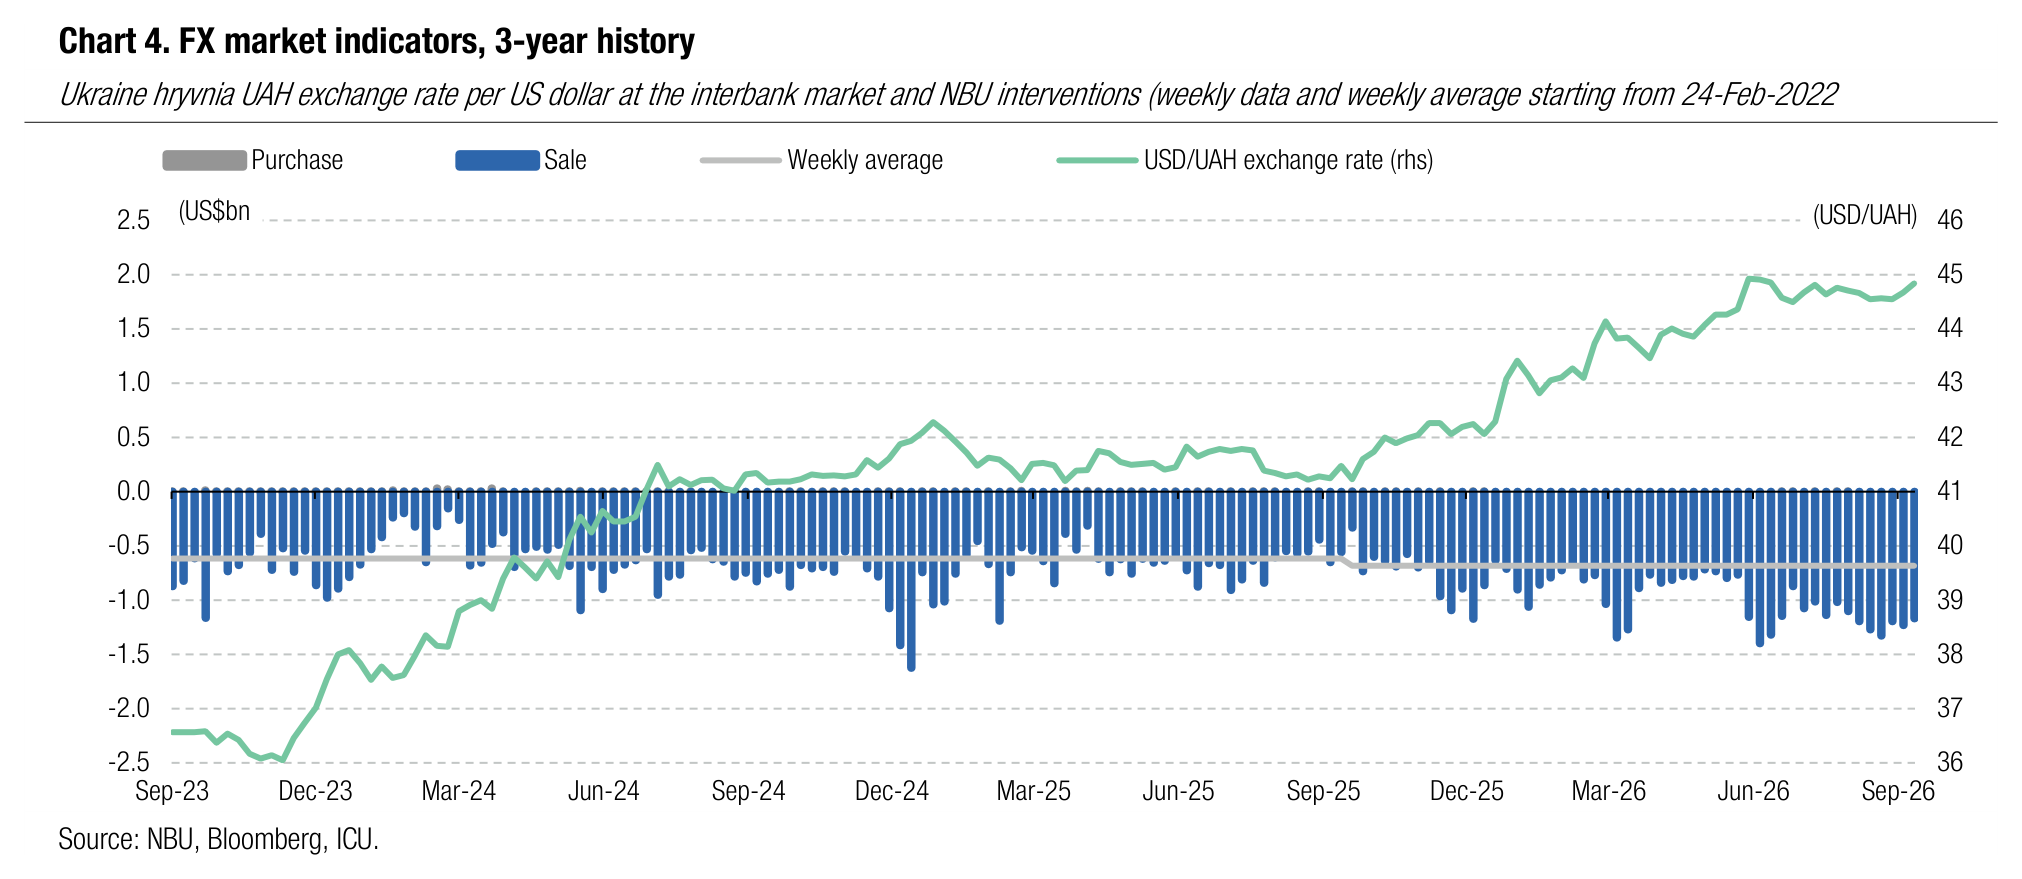
ICU view: While keeping foreign currency sales almost unchanged, the National Bank allowed the hryvnia to weaken slightly, thereby continuing to signal the flexibility of its exchange rate. The hryvnia's performance on Friday effectively demonstrated the NBU's reluctance to allow a significant devaluation at this stage, and its intention to keep the fluctuation range slightly below UAH45/US$. We anticipate that by the end of the year, the NBU will gradually move the exchange rate toward the UAH45.8/US$ while avoiding sharp moves.