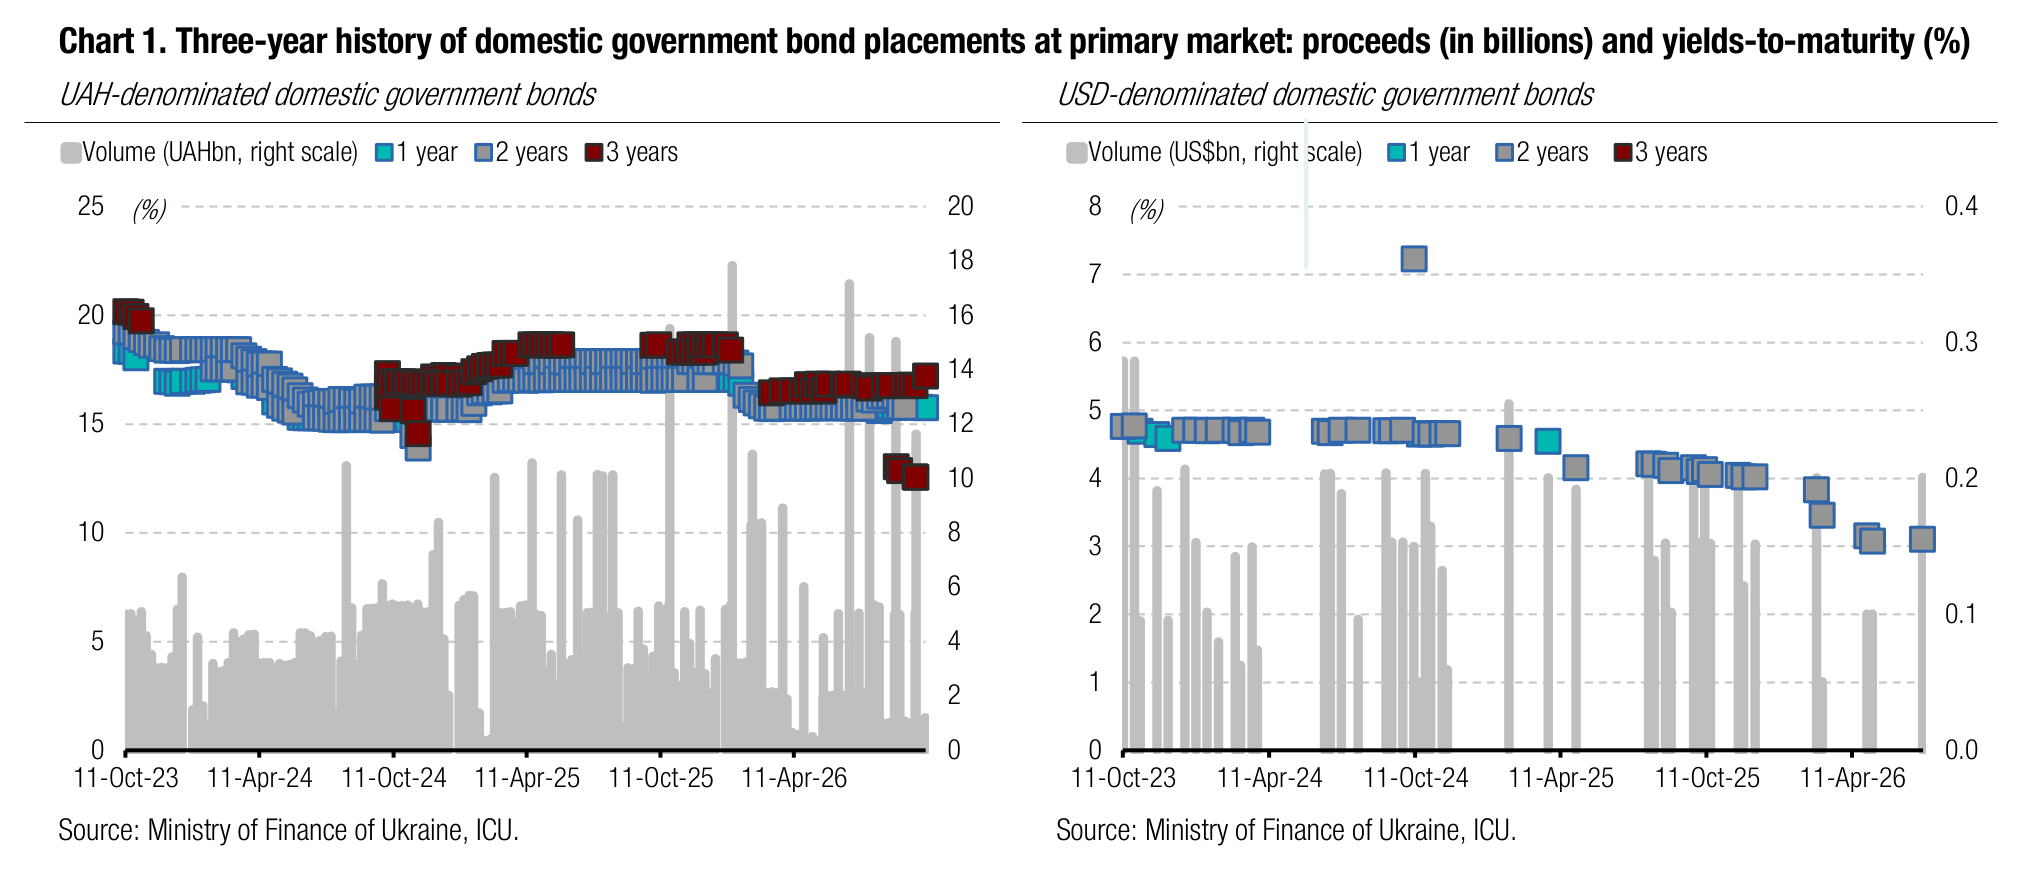

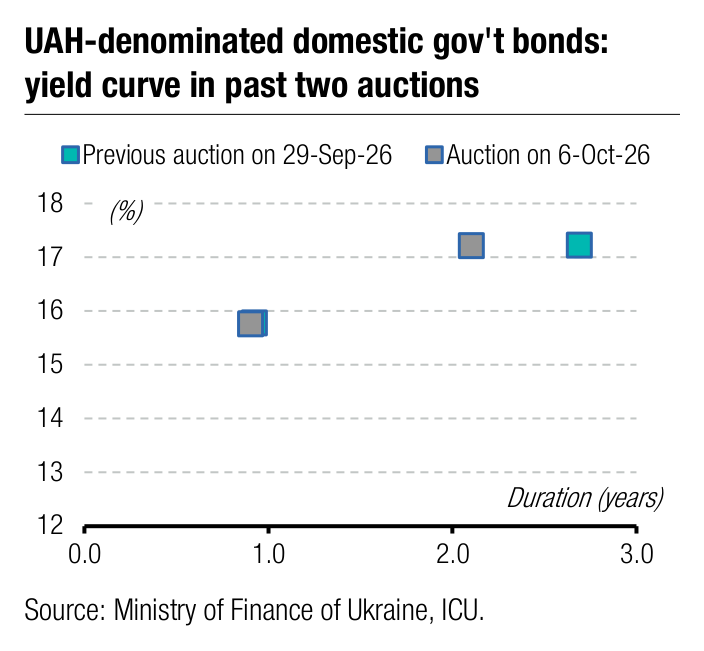
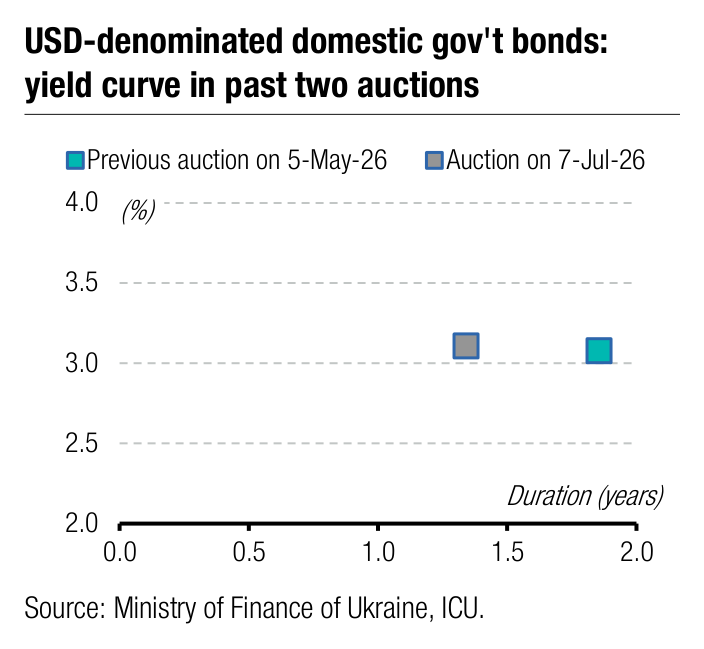
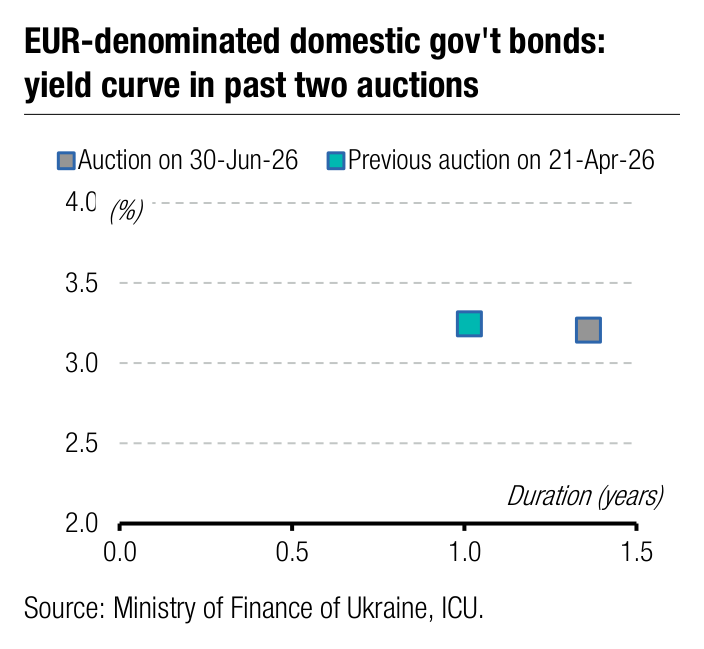
Yesterday, the Ministry of Finance offered a new series of UAH bonds. While the yield was notable, the placement failed to provide the desired volume of funds.
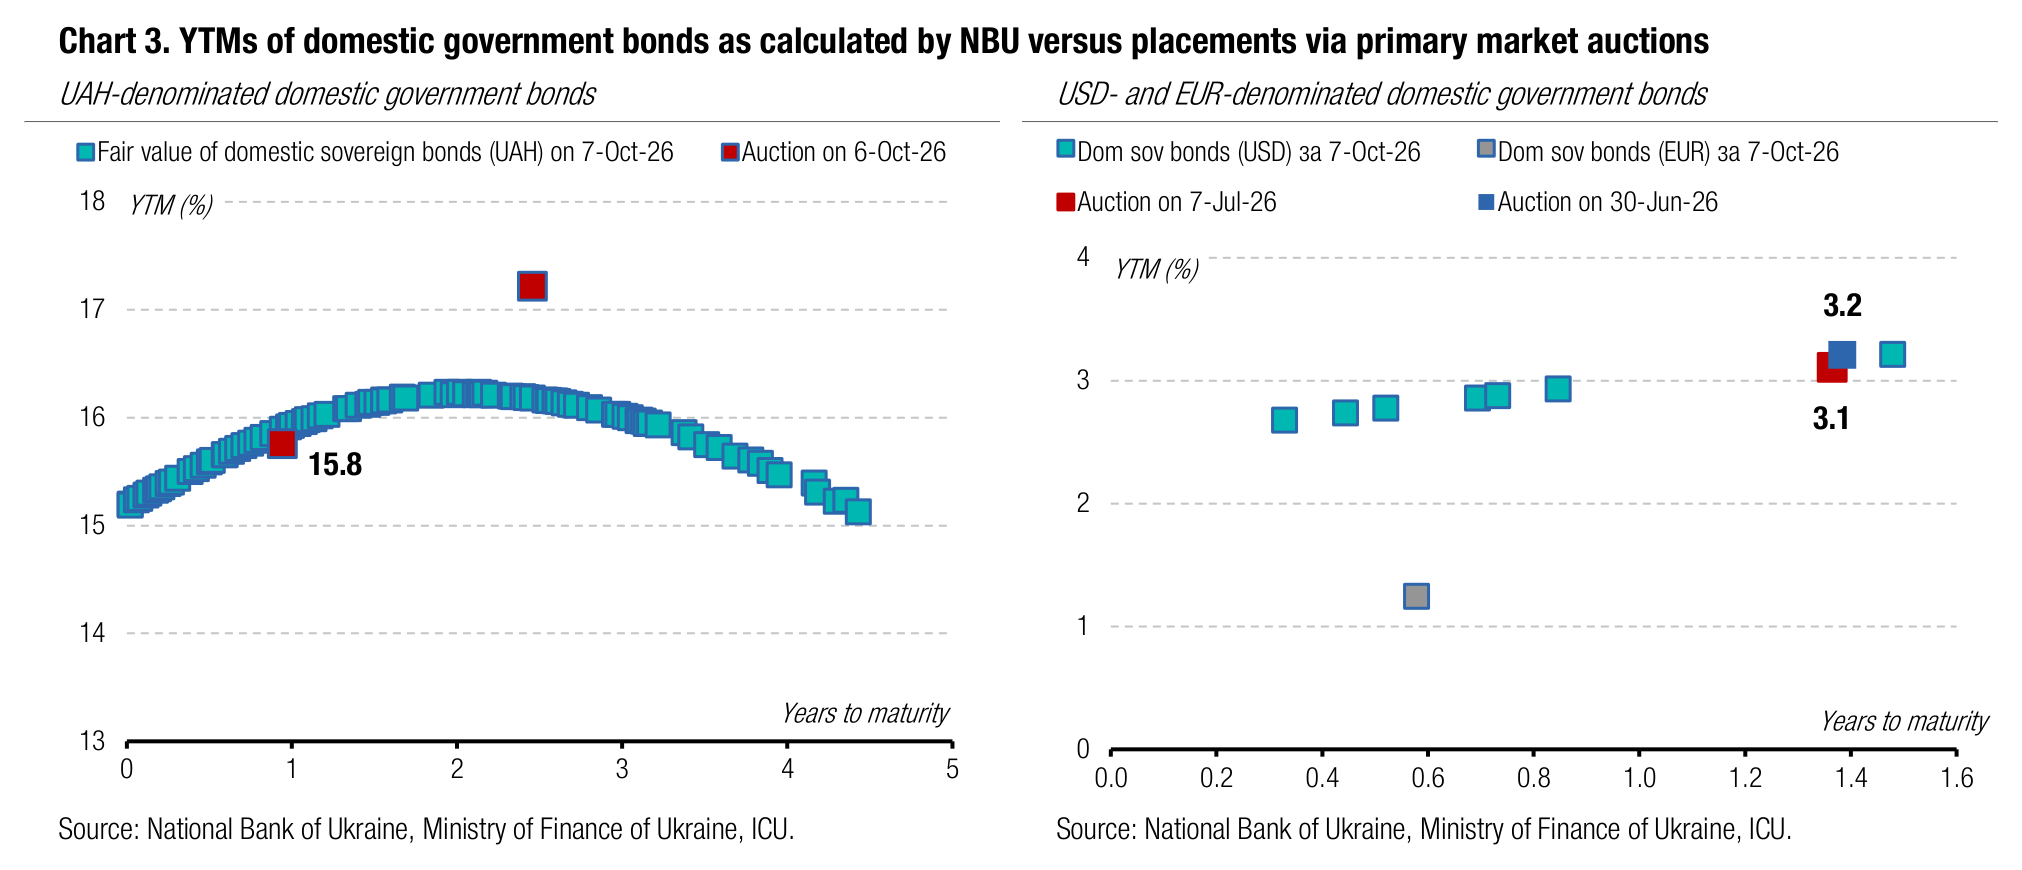
The standard 11-month military bill was, as usual, oversubscribed, bringing just over UAH1bn into the budget. The bid-to-cover ratio was x2.6, with bid yields ranging from 15.1% to 15.18%. However, the offered volume was fully allocated, resulting in a 2bp yield decline to 15.15% and 15.14% for the cut-off and weighted average, respectively.
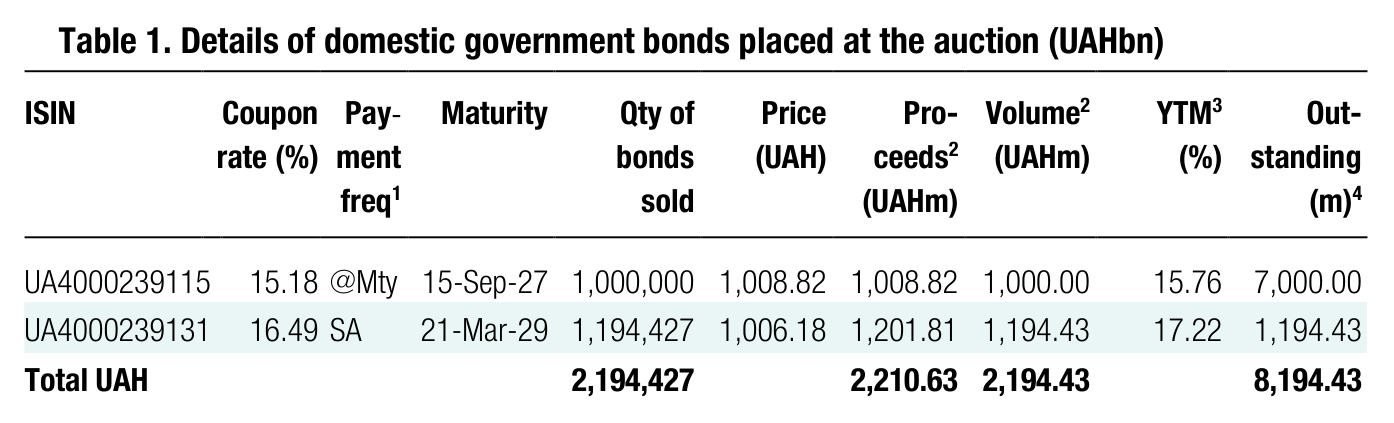
Note: [1] payment frequency abbreviations: M - monthly, Qtly - quarterly, SA - semi-annually, @Mty - at maturity date; [2] proceeds and volumes for the USD-denominated bonds are calculated based on the previous day's exchange rate 44.48/USD, 51.04/EUR; [3] yields on coupon-bearing bonds are effective yields to maturity. Sources: Ministry of Finance of Ukraine, Bloomberg, ICU.
The most interesting story, however, was the placement of 2.5-year bond. Based on all indicators—maturity, offering size, and the exchange auction scheduled for October 21 (allowing the swap of reserve bonds for this new issue)—these were expected to be reserve bonds attracting significant demand and relatively low rates (in September, similar securities were placed at a rate slightly above 12%).
Instead, total demand for the new paper fell well short of the offering—UAH1.6bn vs UAH5bn cap—and featured unusually high bid rates, ranging from 16.1% to 18.78%. The Ministry limited the rate to 16.5% and rejected two bids with higher yields, placing UAH1.2bn of bonds at a coupon rate of 16.49% (the auction's weighted average yield).
The future of this paper will become clear in the coming weeks, whether an auction to exchange reserve bonds will be held in two weeks. The auction will depend on the NBU's decision to add new paper to the list of reserve securities.
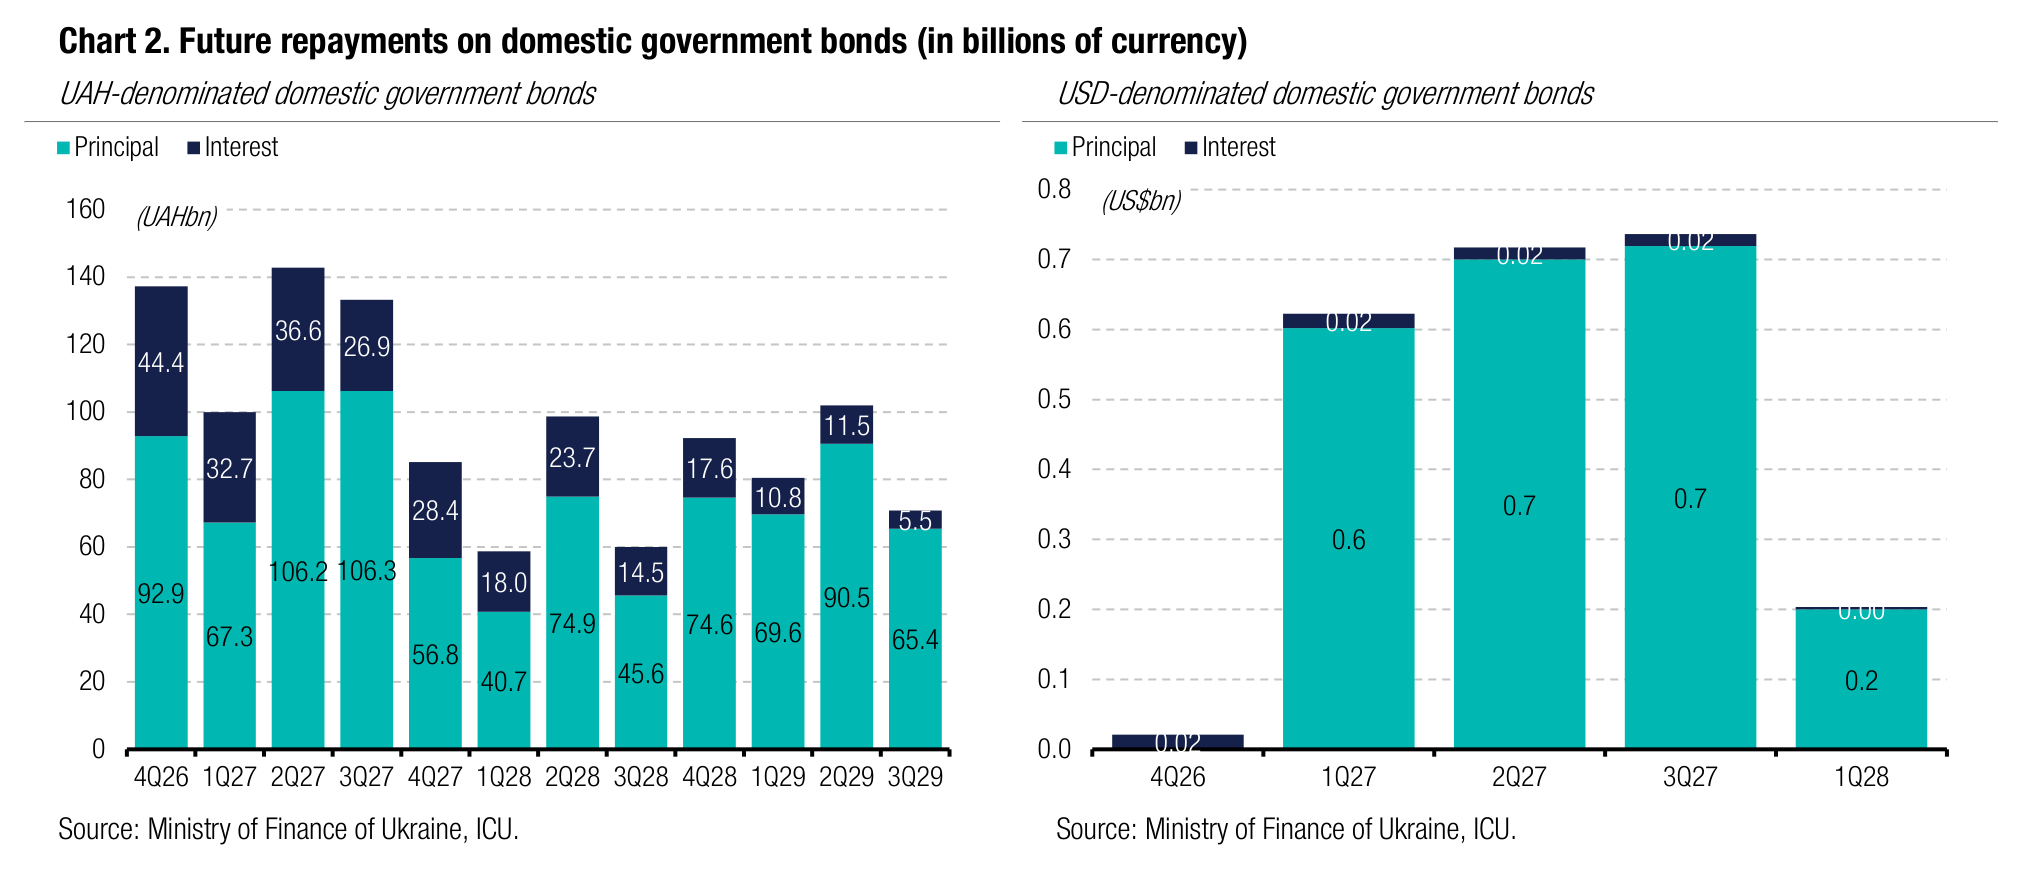
Appendix: Yields-to-maturity, repayments