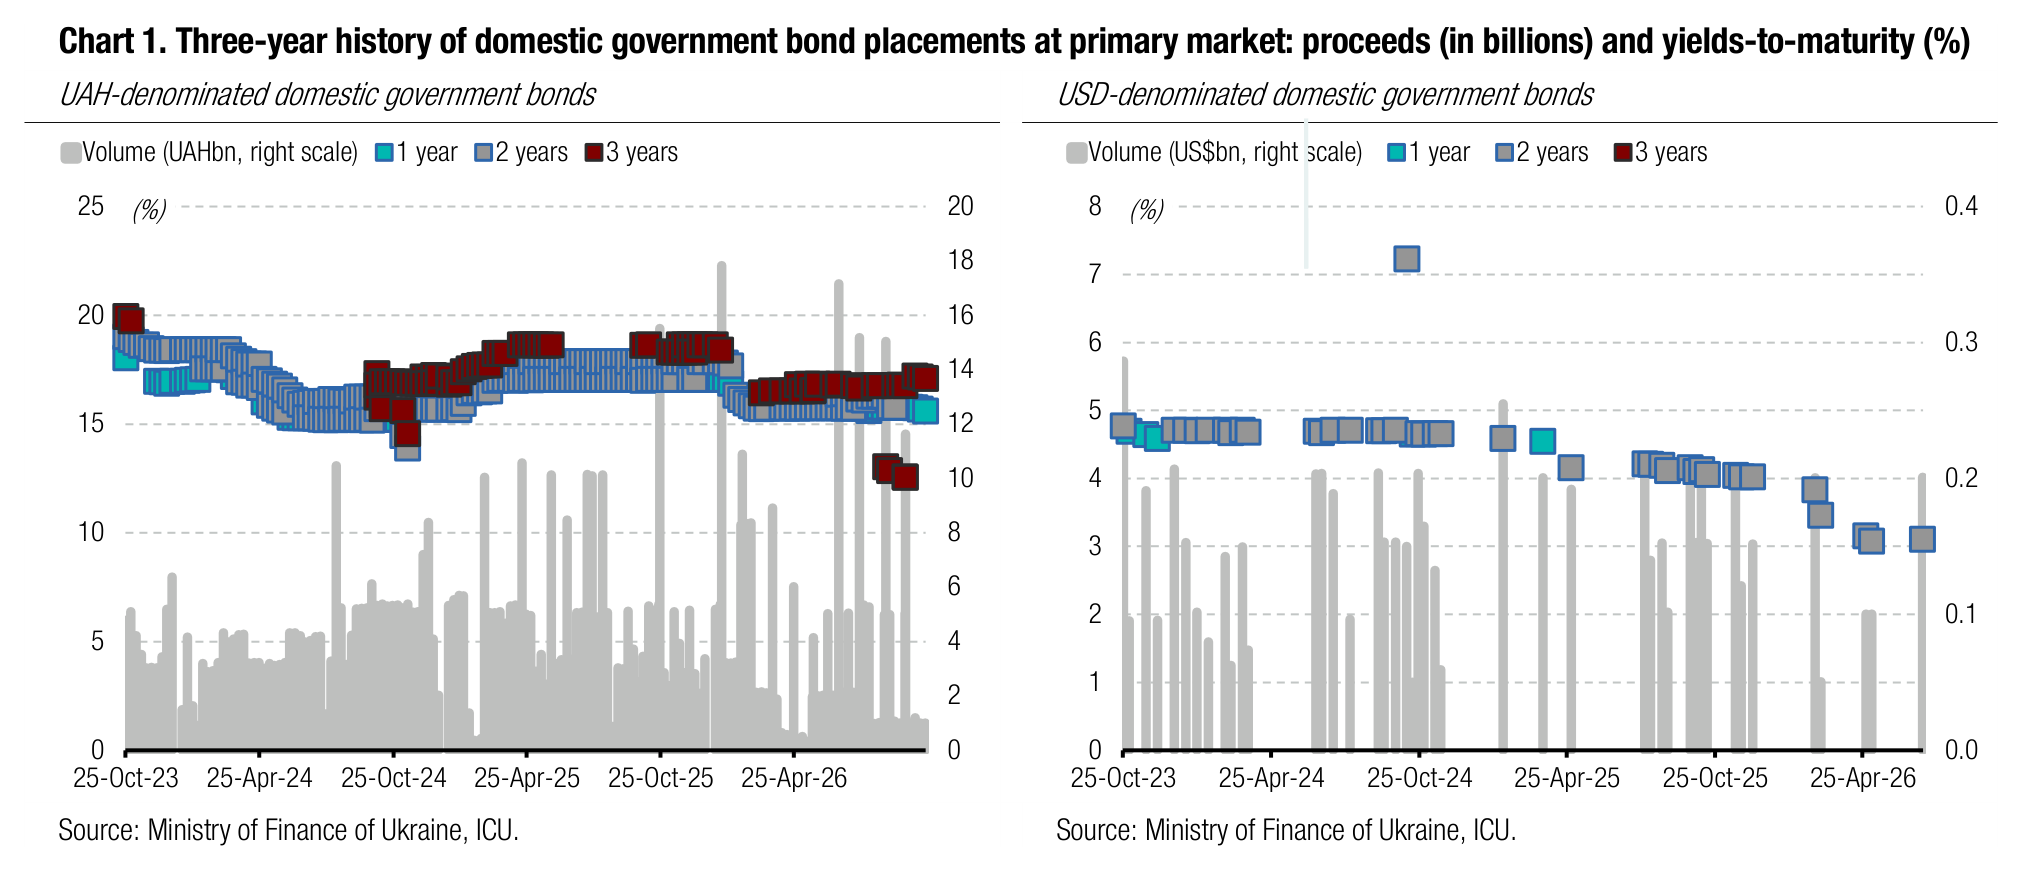

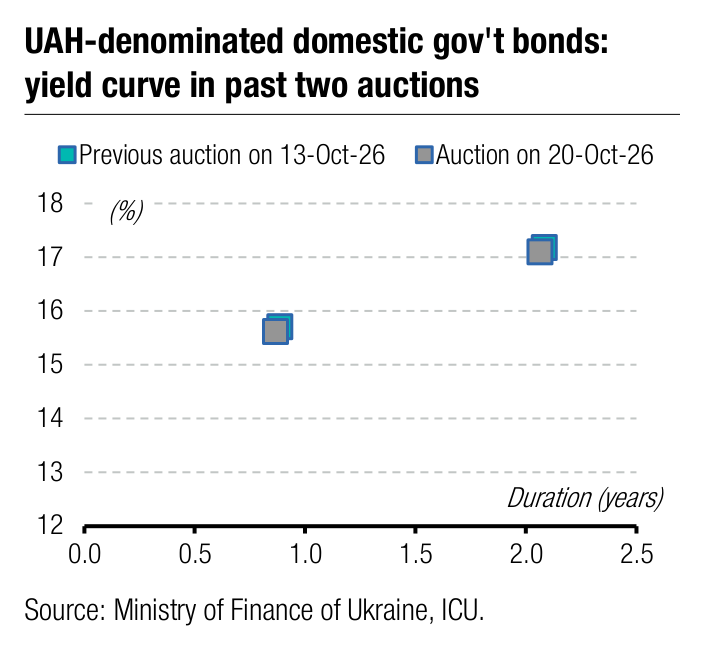
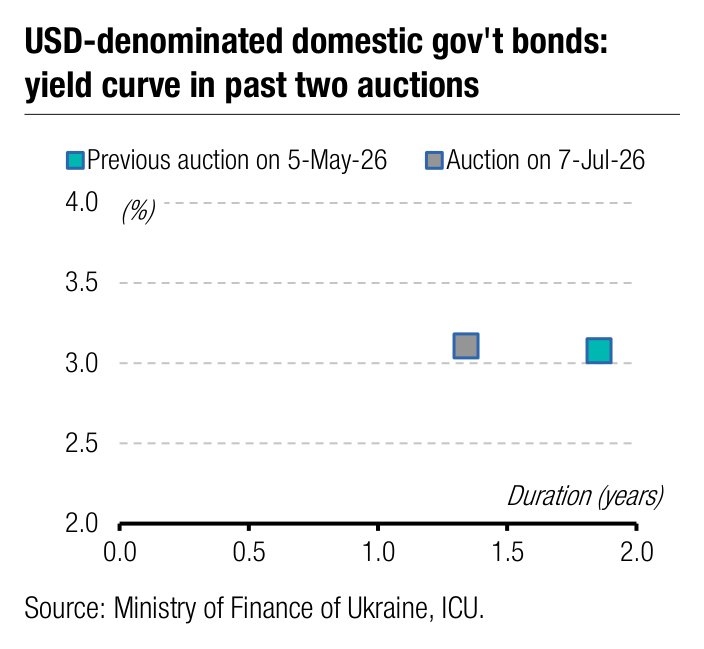
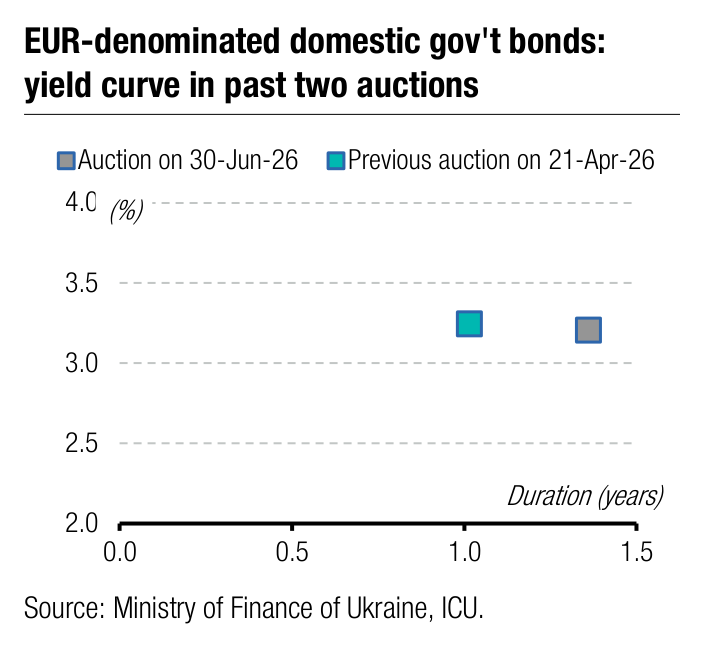
Yesterday, the Ministry of Finance offered the same securities as in the previous two weeks. Two issues—maturing in September of next year and March 2029—attracted a significant volume of bids, which drove yields lower.
The 11-month military bills saw significant demand, resulting in a bid-to-cover ratio of 5.5. The minimum yield fell to 14.98%, and the cap was absorbed at a bid rate of 15.03%—down 6bp WoW. Low bid rates pushed the weighted-average yield down by 8bp WoW to 15.01%.
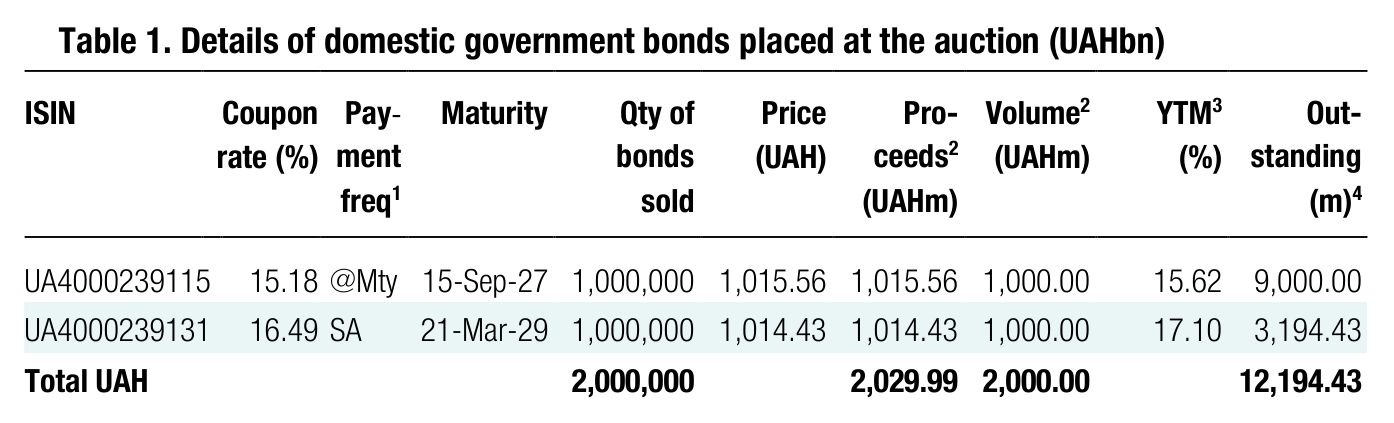
Note: [1] payment frequency abbreviations: M - monthly, Qtly - quarterly, SA - semi-annually, @Mty - at maturity date; [2] proceeds and volumes for the USD-denominated bonds are calculated based on the previous day's exchange rate 44.48/USD, 51.04/EUR; [3] yields on coupon-bearing bonds are effective yields to maturity. Sources: Ministry of Finance of Ukraine, Bloomberg, ICU.
Total demand for the 2.5-year bond was slightly lower, but still exceeded supply with a bid-to-cover ratio of 3.4. Although the minimum bid rate actually rose by 1bp, this did not affect the outcome. Instead, other bids appear to have shifted lower, with the entire offering absorbed at a rate of 16.4%. The weighted-average yield was set at 16.38%. Both figures are 7bp lower than last week.
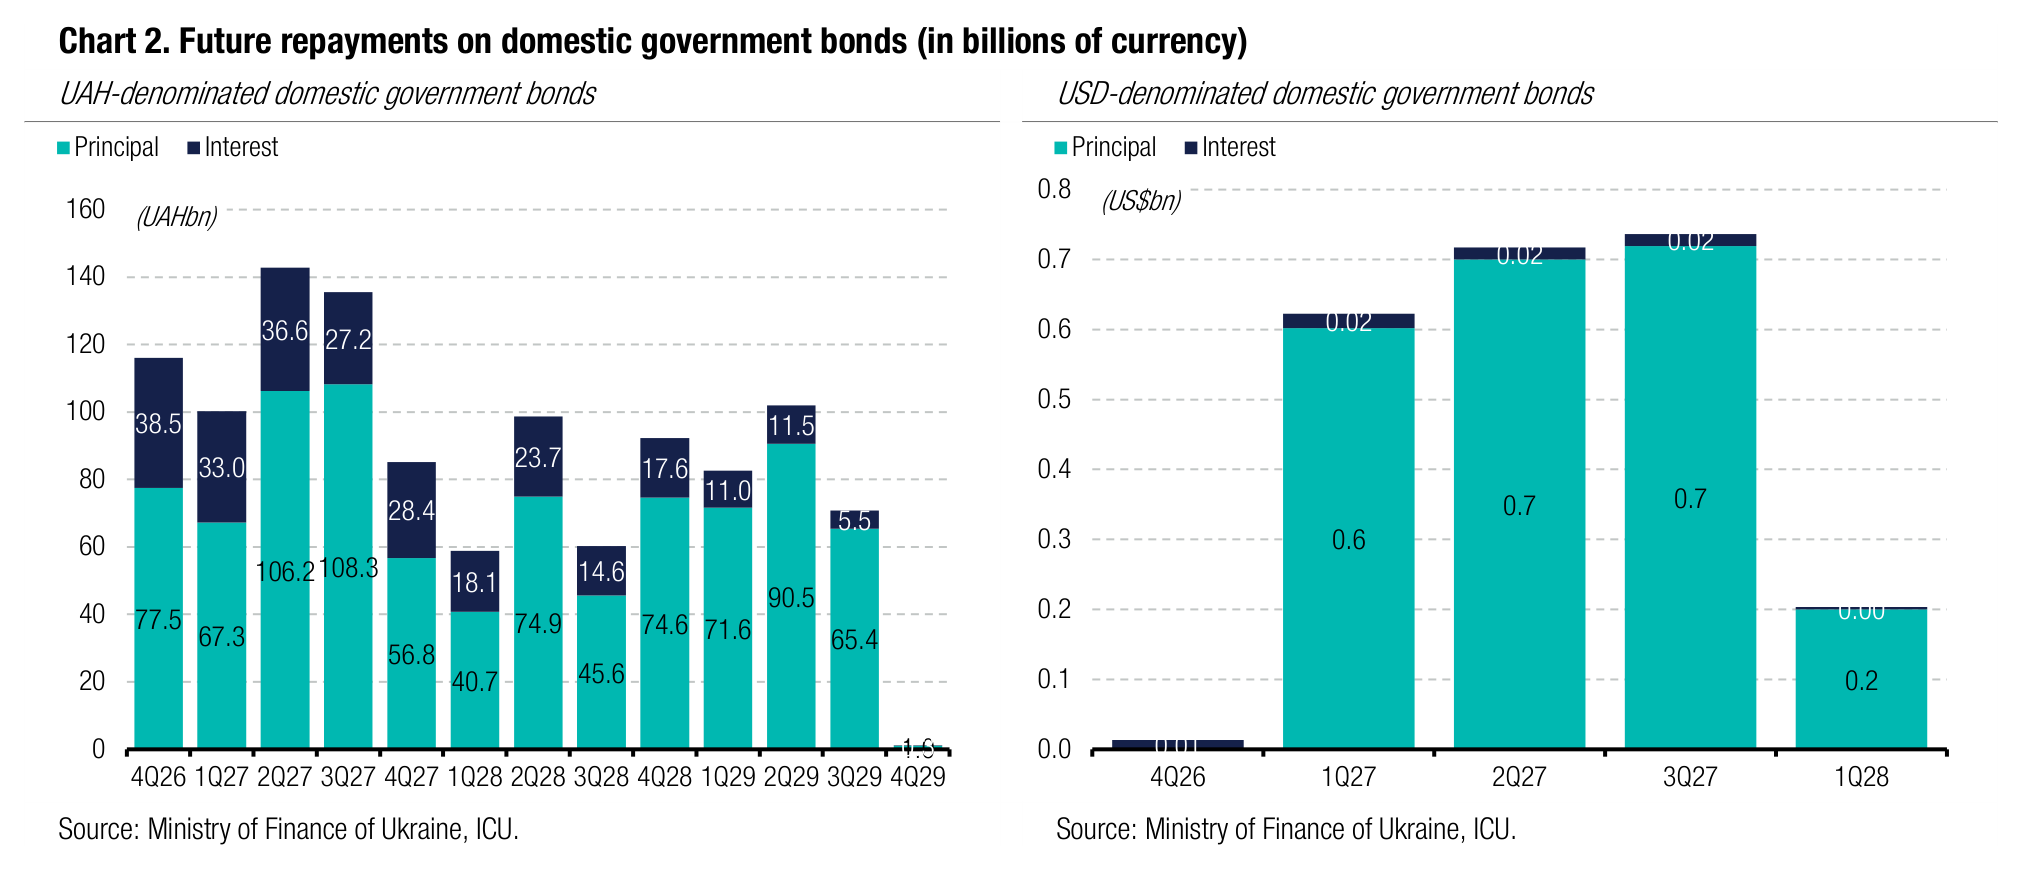
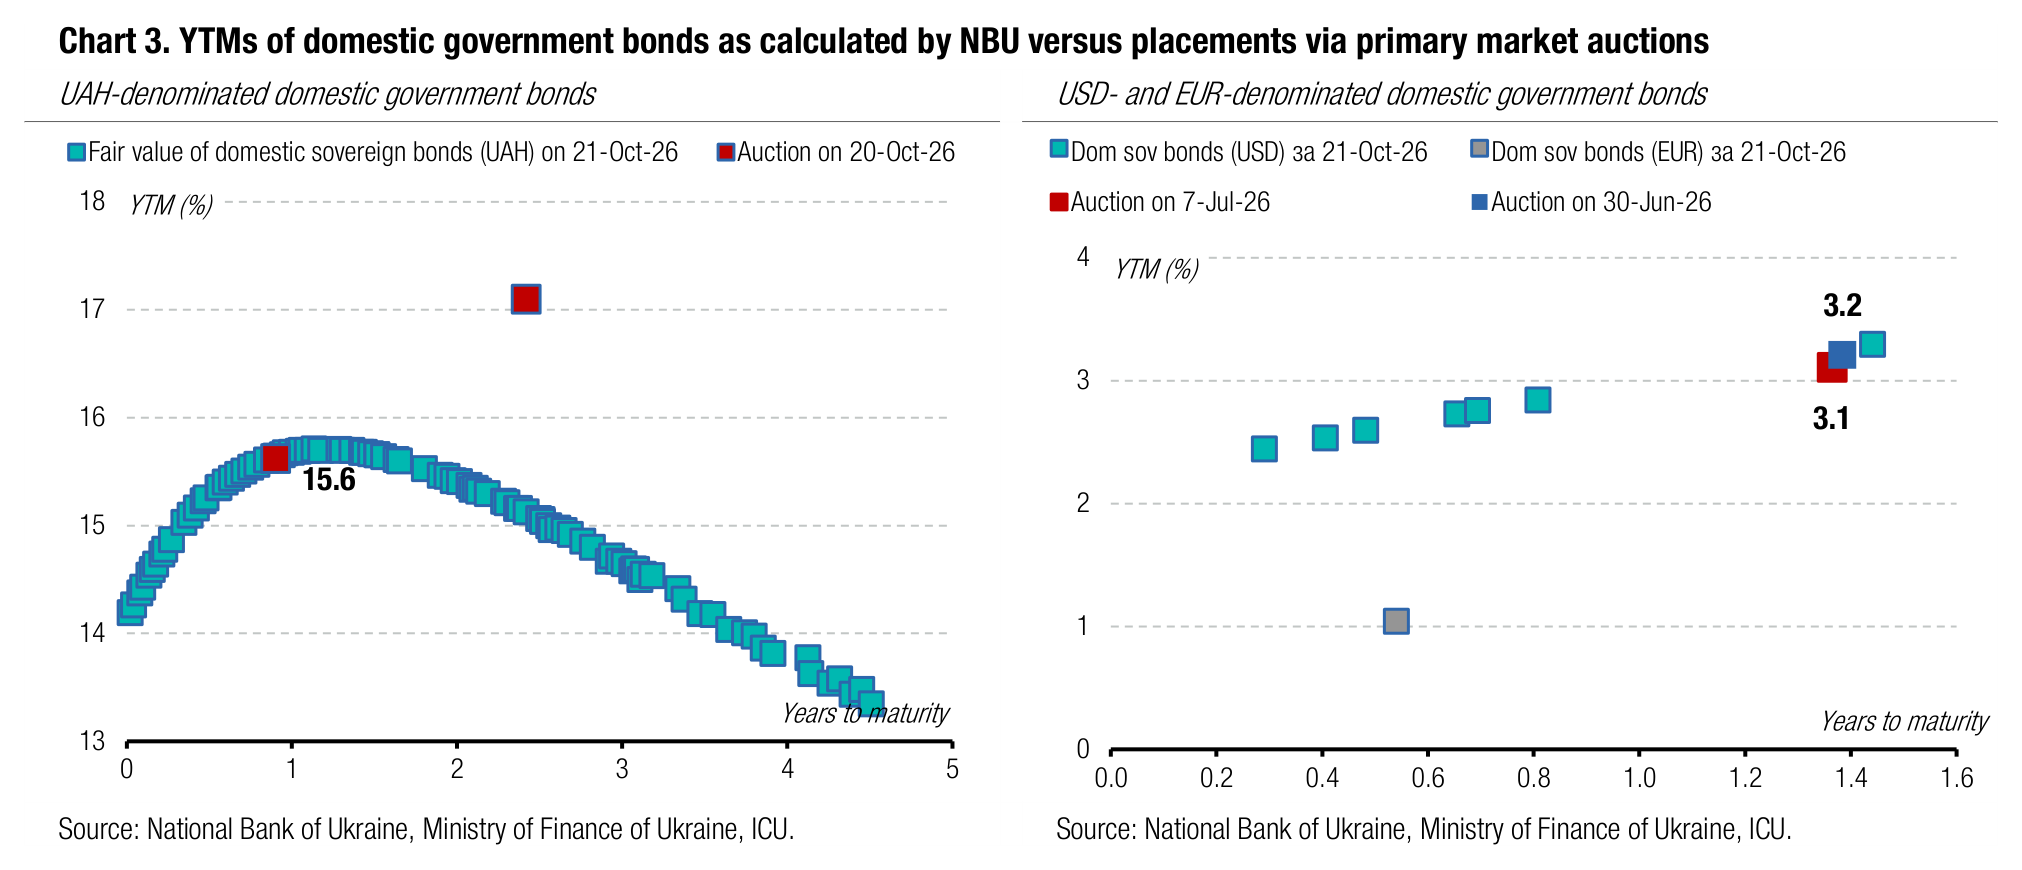
Appendix: Yields-to-maturity, repayments