
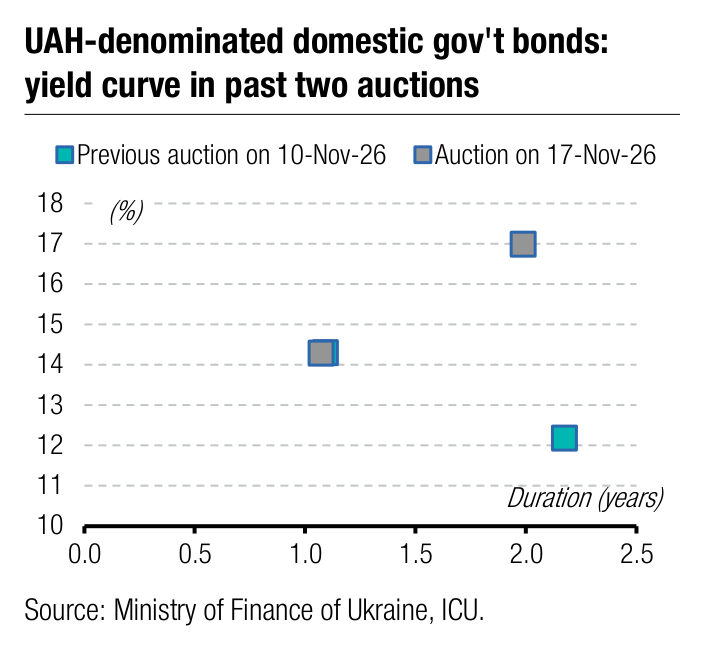
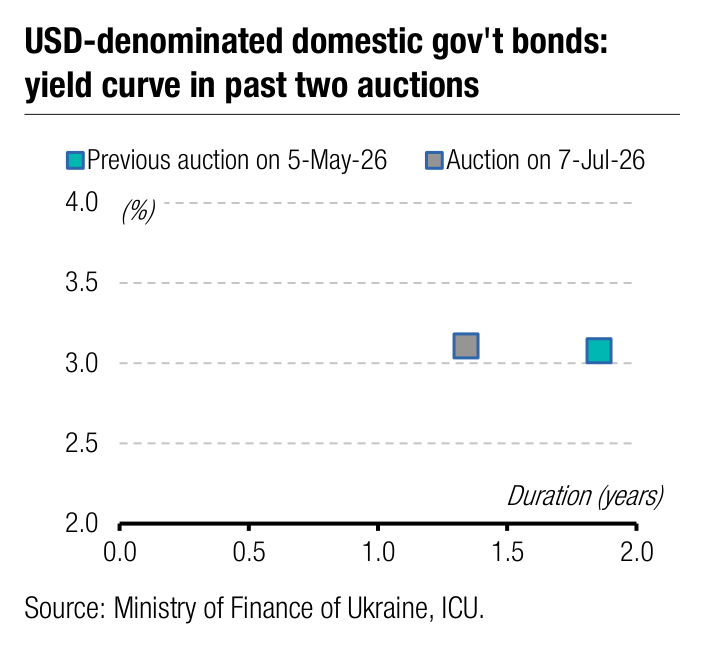
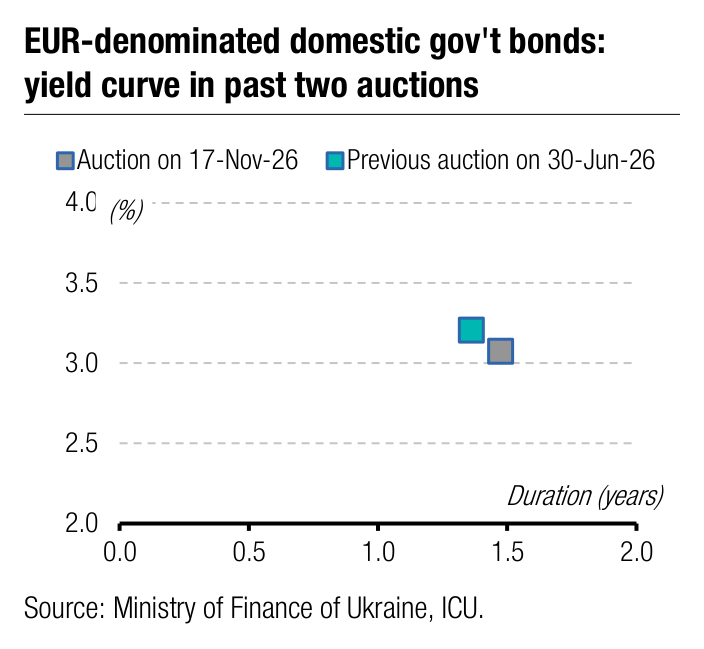
In addition to UAH instruments, the Ministry of Finance also offered EUR- denominated bonds yesterday—the first since early July. This offering raised significant funds, substantially reducing the MoF's borrowing requirements to meet the budget plan.
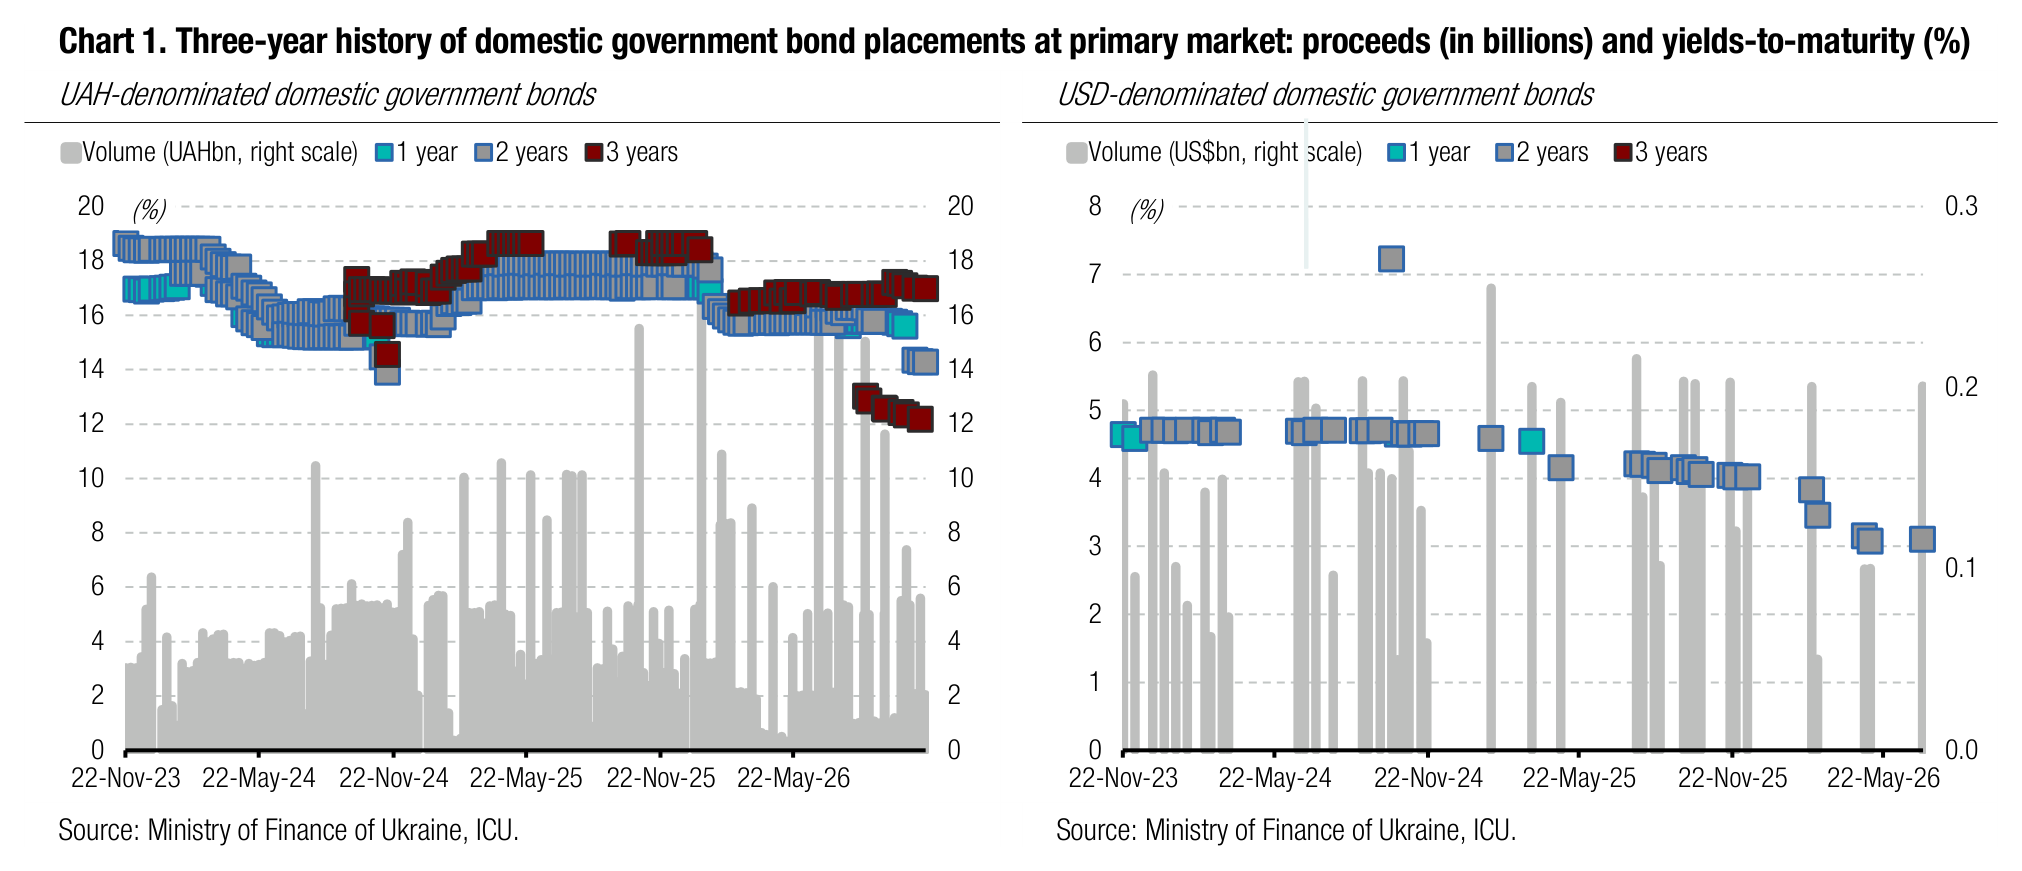
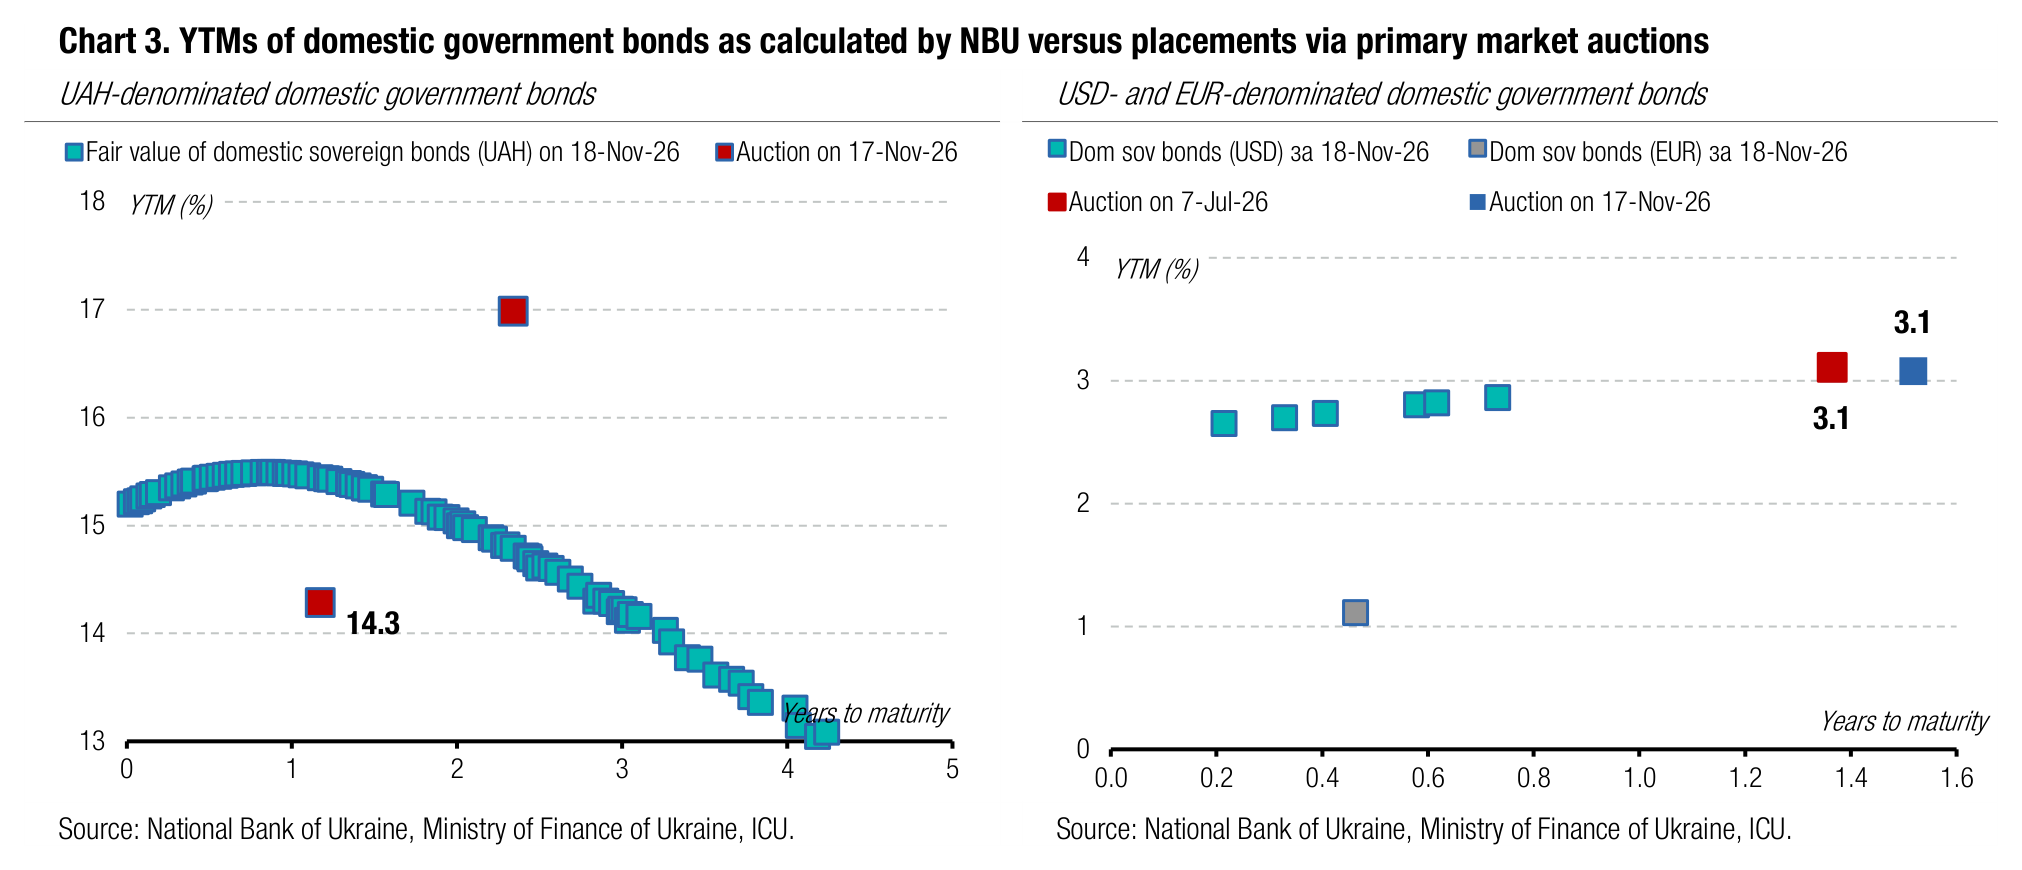
The 14-month UAH military bill unexpectedly drew bids totalling UAH1.3bn—only 67% of the amount offered—even though similar instruments had consistently been oversubscribed since the beginning of autumn. However, the Ministry of Finance refused to raise the cut-off rate by 10bp and rejected a bid at 15.2%. Consequently, the cut-off rate remained at 15.1%—the same level as the previous two weeks—while the weighted average yield rose slightly, by 1bp, to 15.07%.
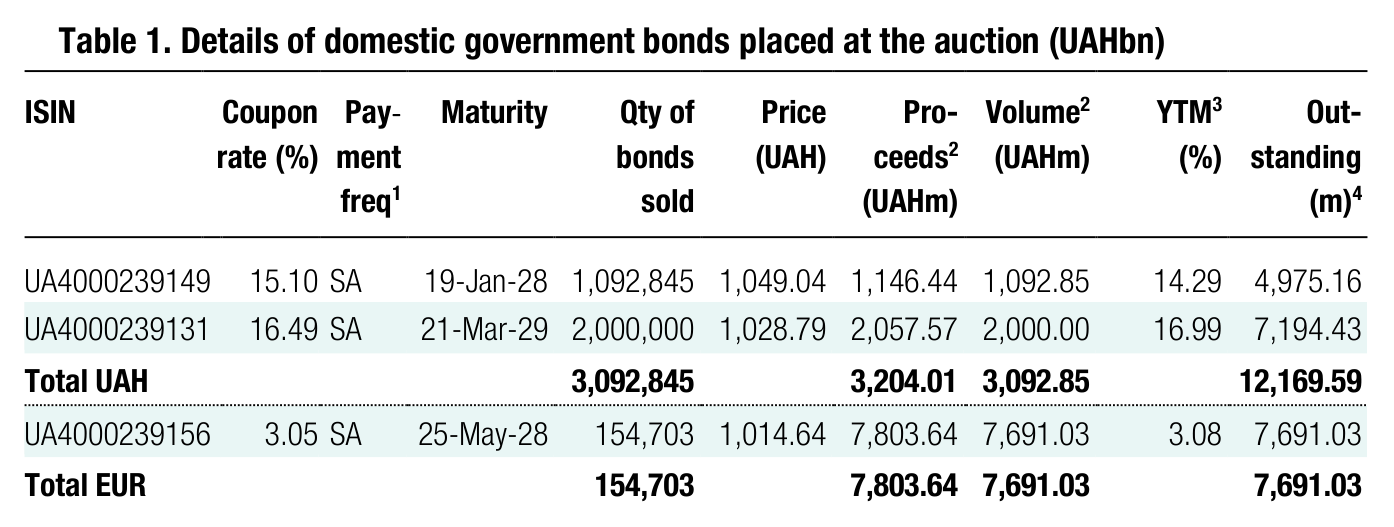
Note: [1] payment frequency abbreviations: M - monthly, Qtly - quarterly, SA - semi-annually, @Mty - at maturity date; [2] proceeds and volumes for the USD-denominated bonds are calculated based on the previous day's exchange rate 44.48/USD, 49.71/EUR; [3] yields on coupon-bearing bonds are effective yields to maturity. Sources: Ministry of Finance of Ukraine, Bloomberg, ICU.
The 2.4-year bond continued to attract strong interest, drawing 34 bids totalling nearly UAH4.6bn (2.3x bid-to-cover ratio). Given this level of competition, the cut-off rate slid by 2bp to 16.28%, and the weighted average yield decreased by 3bp to 16.27%.
The main surprise of the week was the offering of EUR-denominated paper. It was on the auction schedule, but there were no redemptions in this currency scheduled for November or December. The Ministry of Finance offered EUR200m of the paper, but did not see demand for the full amount. A total of 57 bids were submitted, amounting to nearly EUR155m. All bids were at rates of 3.2% or lower—matching the cut-off rate from the auction held in early July. Consequently, the Ministry accepted all bids, resulting in a 3bp decrease in the weighted average yield compared to July, bringing it to 3.05%.
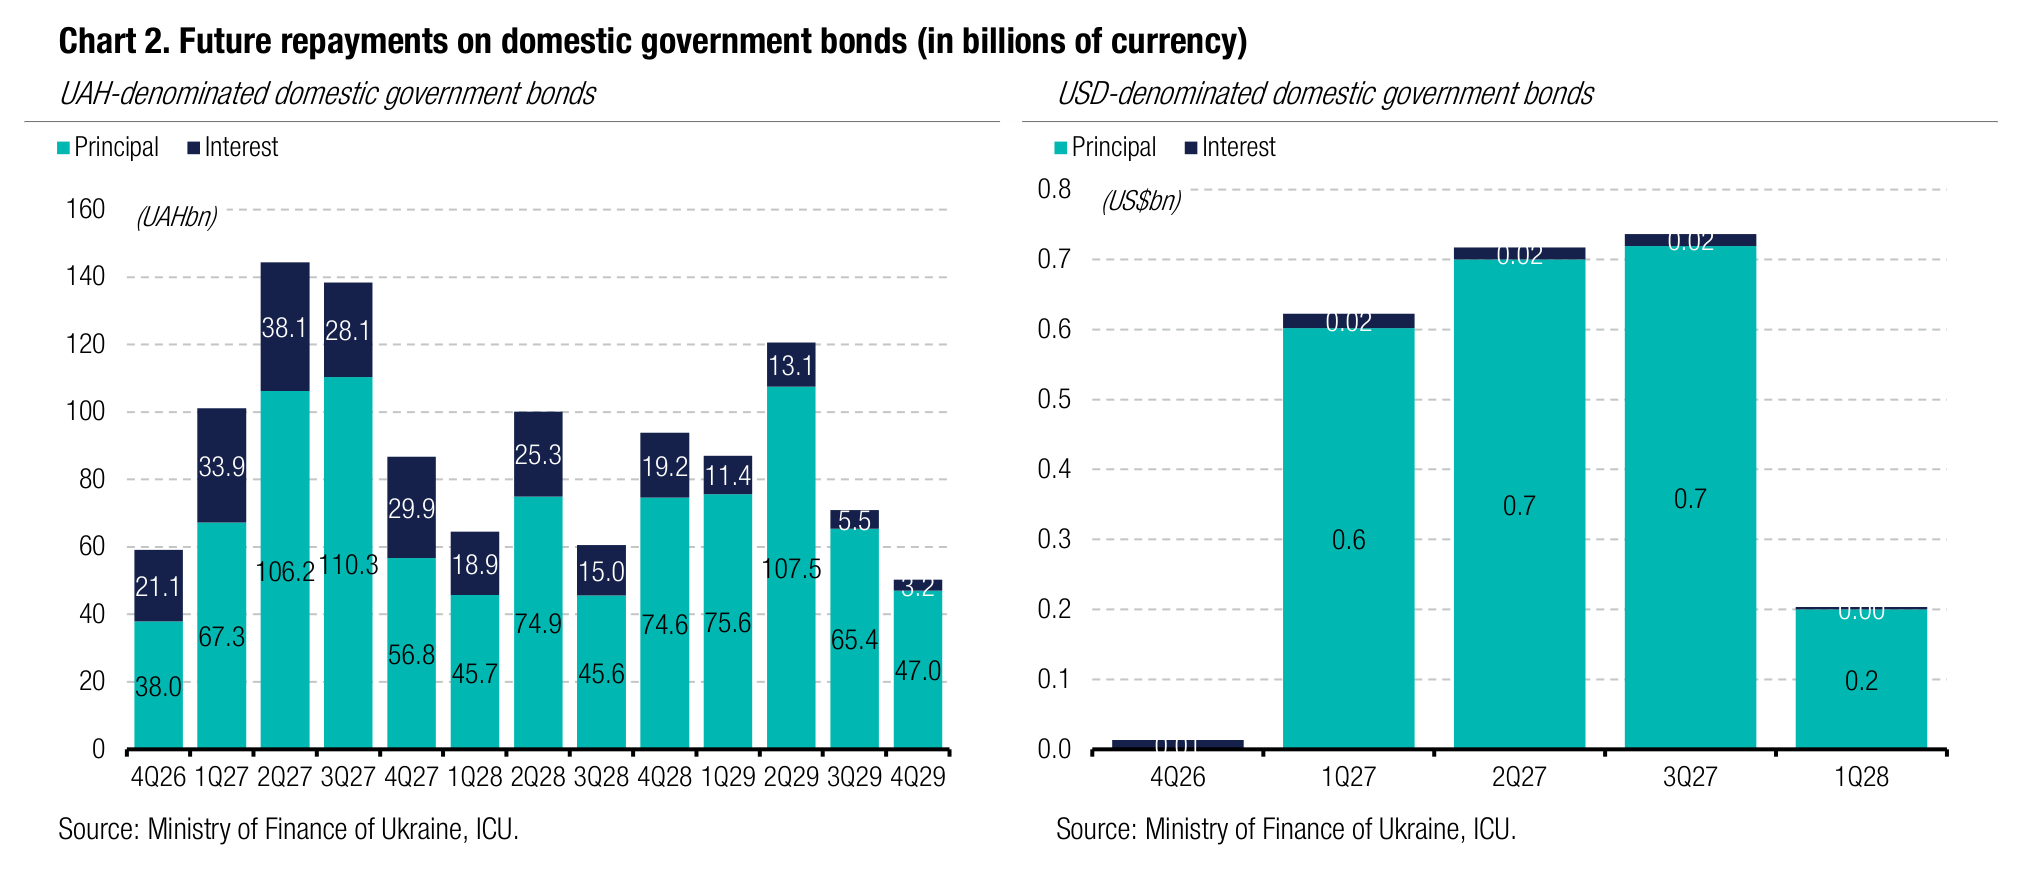
Thus, to meet the current budget plan, the Ministry of Finance needs to borrow approximately UAH10bn—or UAH2bn per week—through the end of the year. This is entirely feasible without requiring any adjustments to the yields on UAH instruments.
Appendix: Yields-to-maturity, repayments